Day Hagan Catastrophic Stop Update October 5, 2026
A downloadable PDF copy of the Article:
Summary
The Day Hagan Catastrophic Stop declined to 54.55% from 59.09% last week. The evidence supports remaining invested, but caution is increasing. Our Catastrophic Stop Model remains above its sell threshold, while weakening stock and high-yield bond participation signal deterioration. Strong earnings revisions and AI investment provide support, and pessimistic sentiment creates rebound potential. Credit spreads show limited financial stress. However, higher yields, rising bond volatility and persistent inflation complicate an expanding economy with slower hiring.
The Day Hagan Catastrophic Stop Model declined to 54.55% from 59.09% last week as High Yield Bond Breadth narrowed further. The message is to remain invested while watching for further deterioration.
Figure 1: The model remains constructive, although its margin of safety is still narrow. A reading below 40% for two consecutive days would trigger a sell signal and call for reduced equity exposure or higher cash levels.
The chart below shows widespread weakness beneath the S&P 500’s surface. As of October 2, 426 stocks were at least 10% below their all-time highs, 307 were down at least 20%, and 98 were down 50% or more. These categories overlap, and the declines may span years. Rising counts suggest deterioration, although the deepest losses remain less widespread than during major crises.
Figure 2: 426 stocks within the current S&P 500 are 10% or more below their all-time highs.
As of October 2, 421 stocks were at least 10% below their five-year closing highs, 281 were down at least 20%, and 65 were down at least 50%. It is more useful for assessing current conditions because the previous chart measured declines from all-time highs, which can include peaks reached decades ago. The five-year window reduces that historical baggage. Severe declines fall from 98 stocks to 65, but broad weakness remains. This strengthens the breadth warning, although neither chart alone establishes a market sell signal.
Figure 3: 421 stocks within the current S&P 500 are 10% or more below their five-year closing highs.
The Day Hagan Sentiment Composite fell to 31.35, just above its 30 pessimism threshold, despite the S&P 500 remaining near highs. Investors appear increasingly cautious. That can support a contrarian rebound, but does not establish a market bottom.
AAII’s October 1 survey similarly showed 46.5% bearish versus 34.6% bullish, although pessimism eased that week. NAAIM exposure, reported October 2 at 76.99, suggests active managers remain substantially invested despite some retreat. Together, these readings suggest unease without wholesale capitulation. Improving breadth would strengthen the case for a sustained recovery.
Figure 4: Sentiment continues to illustrate significant investor pessimism.
This chart also indicates substantial weakness beneath the market’s surface. Only 27.47% of Russell 3000 stocks were above their 50-day moving averages, below the chart’s 30% oversold threshold, while the S&P 500 remained near its highs.
That reinforces the previous chart. Both suggest the headline index is masking widespread weakness.
The distinction is timing. The previous chart measures distance from past peaks. This one measures shorter-term trend participation across a broader universe. Together, they suggest many stocks have already undergone a correction. Oversold conditions create rebound potential, but improving breadth—particularly a recovery above 30%, then 45%—would provide stronger evidence that participation is recovering.
Figure 5: Breadth still narrow = caution flag.
High-yield bond breadth at −21.58, below the −10 warning threshold, reinforces weak stock participation and cautious sentiment. Weakness extends into credit, suggesting oversold equities need broader confirmation before a rebound looks durable.
Figure 6: High-yield breadth signals caution.
Credit spreads remain below historical averages, indicating limited concern about defaults. Despite weakening high-yield breadth, credit pricing has not confirmed widespread financial stress, providing a counterweight to the recent caution signals.
Figure 7: U.S. Credit spreads (OAS) still tight.
The scorecard’s 3.75 out of 10 reading points to a challenging backdrop for U.S. equities. Strong earnings expectations and AI investment remain important supports, but higher bond yields, narrow market participation and softer hiring limit confidence. Consumer spending is holding up, although income growth provides less support. Broader participation, stabilizing yields and improving credit conditions would strengthen the case for taking more risk.
Figure 8: Several major longer-term factors influencing the market are becoming less supportive.
Portfolio Outlook
The table highlights a sharply divided market. Energy and technology lead year to date and are the only sectors above both their 50-day and 200-day averages. Nine sectors trail the S&P 500, underscoring narrow leadership. Financials and real estate show particularly weak momentum, with RSI readings suggesting oversold conditions. Technology’s elevated short-term RSI suggests a more extended advance. Strong projected earnings growth supports the broader market, but improving participation would make the advance more convincing.
Figure 9: S&P 500 Sector Fundamentals and Technicals. Technical shading: green = strong; yellow = neutral/mixed; red = weak.
Sector Weekly Updates
For the week ended Friday, October 2, 2026, the S&P 500 declined 0.3% on a price-return basis, the Nasdaq Composite gained 0.5%, and the Dow fell 1.3%. Friday’s rally followed weaker-than-expected employment data, which reduced expectations for another near-term Federal Reserve rate increase. However, the rebound did not erase the broader market’s weekly losses. Technology, Energy, and Utilities were the only sector ETFs to advance, while Health Care and Financials posted the largest declines.
Consumer Discretionary declined 0.5%. Friday’s rebound limited the weekly loss, but the sector still struggled to establish broader strength. Slower hiring adds another consideration for household spending alongside borrowing costs.
Consumer Staples declined 1.9%. Essential purchases did not translate into defensive stock performance. The decline reinforces the need to distinguish stable demand from an attractive valuation.
Communication Services declined 2.3%. The sector reversed the previous week’s advance and lagged Technology substantially. That divergence shows why digital platforms, media, and telecommunications should not be treated as a single AI investment. Energy gained 1.3%. The sector recovered part of the prior week’s decline despite mixed crude-oil performance.
Financials declined 2.5%. The sector remained under pressure as investors weighed elevated yields against a softer employment backdrop. Higher lending yields are only one part of the earnings equation. Funding costs, loan demand, credit quality, and securities valuations remain central to determining which companies can benefit from the rate environment.
Health Care declined 2.6%, the weakest sector. The reversal from the previous week’s gain illustrates that less cyclical demand does not guarantee near-term downside protection.
Industrials declined 0.3%. Gains late in the week recovered most of the earlier weakness. The comparatively small loss was encouraging, although it offered limited evidence of a broad acceleration in industrial activity. Our focus remains on order quality, backlog conversion, and whether investment in infrastructure and productive capacity translates into stronger cash flow.
Information Technology gained 1.8%, leading all sectors. AI infrastructure and semiconductor developments remained prominent, while Technology’s advance contrasted with losses across most of the market. Continued leadership supports the broader index, but also increases its dependence on a narrower group of companies. We are watching whether earnings growth and cash generation justify expectations embedded in valuations.
Materials declined 1.9%. The sector’s weakness contrasted with Energy’s gain, underscoring that commodity-related businesses face different demand and cost dynamics. Softer employment data also complicate the growth outlook. We want to see improving orders and margins before interpreting longer-term infrastructure and electrification spending as evidence of a sustained sector recovery.
Real Estate declined 1.8%. Friday’s modest gain was insufficient to reverse the weekly loss. Elevated Treasury yields remain an important hurdle for property valuations and refinancing economics. We continue to favor careful analysis of debt maturities, occupancy, rent growth, and access to capital rather than assuming that reduced Fed-hike expectations resolve financing pressures.
Utilities gained 0.8%. The sector recovered a portion of the previous week’s sharp decline and joined Technology and Energy in positive territory. The improvement is welcome, but one week does not establish a durable reversal. We remain focused on financing requirements, regulatory recovery of investment costs, and how growing electricity demand translates into earnings.
Note. Index figures are weekly price returns. Sector figures are the price returns of the 11 Select Sector SPDR ETFs, calculated from their September 25 and October 2, 2026, closing prices and rounded to one decimal place. They exclude distributions and may differ from dividend-adjusted ETF returns or the corresponding S&P 500 sector index returns.
Figure 10: Sector Relative Strength vs. S&P 500
Reading the chart: “The teal line shows the share above the 50-day average; blue shows the share above the 200-day average. Dashed segments join the reference chart to Friday’s close.”
Source: Supplied chart through Sep 18 (curves traced approximately); Barchart sector moving-average table for Sept 25 endpoints. Percentage rounded by Barchart.
Current constituents may differ from historical membership. Historical traced lines are illustrative. Friday endpoints are source-reported. For informational use.
Technology is the only sector with most stocks above both moving averages. Participation elsewhere is weak, especially financials, real estate and utilities, showing how narrow leadership masks deterioration beneath the market’s headline performance.
Figure 11: Breadth has narrowed. We’re monitoring our suite of indicators for confirmation that this is the beginning of corrective activity or a shorter-term pause.
Equity exposure in a 10% volatility-target strategy (our proxy for vol-targeting funds) has risen past roughly one standard deviation above its five-year average. That suggests systematic investors have added stocks as market volatility has allowed larger positions. The reading is elevated, though well below the chart’s most extreme levels. Continued calm could support demand, while a volatility spike could force these strategies to reduce exposure.
Figure 12: Vol-targeting funds’ exposure now over +1 SD. Another yellow flag (caution).
DBMF’s S&P 500 exposure has climbed to 46.13%, near the upper end of its recent range. Positioning increasingly favors rising equities, but leaves the strategy more exposed if the market reverses.
Figure 13: Positioning indicators remain mixed, but the overall message remains “high neutral.”
Forward earnings estimates rose 9.1% over 63 trading days, a 97th-percentile reading. All sectors show positive revisions, led by technology, providing broad fundamental support despite weak market breadth and some cooling in revision momentum.
Figure 14: Earnings continue to support equities.
The S&P 500 has outpaced its historical cycle composite in 2026. Seasonal patterns suggest consolidation or weakness through October, followed by renewed gains into 2027. Cycles remain supportive, but this year’s returns are front-loaded.
Figure 15: Updated S&P 500 cycle composite for 2026 and 2027.
The scorecard’s 3.17 out of 10 reading signals a difficult backdrop for bond prices, even as higher yields improve income opportunities. Inflation remains above target, Treasury financing needs are substantial, and rising long-term yields pressure existing holdings. Softer hiring strengthens the case for a Fed pause, but does not ensure lower rates. Widening credit spreads also warrant caution toward weaker borrowers. The message favors quality and controlled maturity exposure. Short- and intermediate-term bonds offer attractive income with less interest-rate sensitivity, while longer maturities need greater stability in inflation and yields to become more compelling.
Figure 16: Higher rates are a clear headwind.
Closing in on the upper end of the range.
Figure 17: A visual of the rise in rates.
The entire Treasury curve continues to shifted higher.
Figure 18: Selected Treasury and Mortgage rates.
The MOVE Index’s rise to 107.29 signals greater uncertainty and larger expected swings in Treasury yields. Although below major historical peaks, the increase reinforces caution about longer-duration bonds, whose prices are more sensitive to rate changes. Higher yields improve income opportunities, but investors should expect a bumpier ride, without a clear directional signal.
Figure 19: The MOVE index is providing a much different message than VIX.
U.S. Economic Releases:
Last week’s releases showed continued economic expansion, but a softer labor market and uneven inflation progress. GDP growth was revised to 2.2%, consumer spending rose 0.9%, and manufacturing surveys remained above 50, signaling expansion. However, spending outpaced income growth of 0.2%, consumer confidence fell, and job openings declined. Payrolls increased just 29,000, unemployment reached 4.2%, and wages rose only 0.1%, although low unemployment claims suggested limited layoffs. Core PCE inflation increased a milder-than-expected 0.2%, but ISM manufacturing prices jumped to 77.9. Together, the data support a Fed pause while warning that slower hiring has not eliminated inflation pressure.
Monday’s ISM services report showed continued expansion, but slower momentum. The index slipped to 54.9, new orders remained healthy at 59.8, and employment edged back into growth. However, prices paid rose to 74.0, the highest since July 2022, reinforcing concerns that inflation pressure persists.
Next, watch Wednesday’s Fed minutes for the debate over further tightening, Thursday’s jobless claims for signs of rising layoffs, and this week’s consumer sentiment and inflation expectations. The key question is whether growth can moderate enough to ease inflation without materially weakening employment. Treasury yields and MOVE will show how bond investors interpret that balance.
Figure 20: Economic release calendar. Source: Forexfactory.com
Repeat from last week: More midterm data: Midterm years have historically been uneven for stocks. From 1931 through 2025, the S&P 500 averaged a 4.7% calendar-year price gain in midterm years, versus 9.6% in other years. The average midterm path was weakest around September. The picture improved after voting: the chart shows an average 14.8% price gain in the 12 months following Election Day since 1950. These are historical averages, not a forecast. Economic conditions, earnings, and interest rates still shape each cycle.
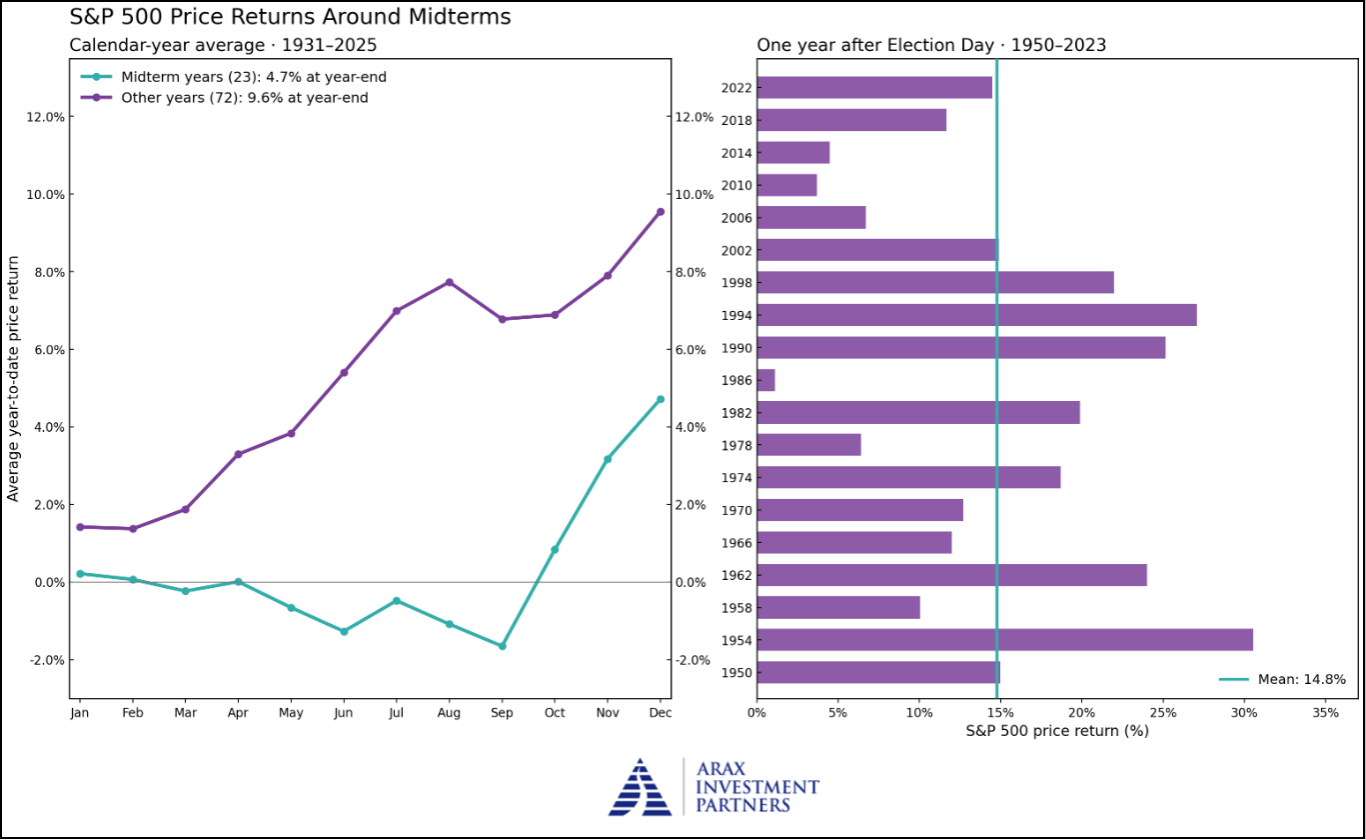
Figure 21: Whether a midterm year or not, equities have tended to find a bottom during the September/October period.
Bottom Line
The overall message is to remain invested while recognizing growing risks beneath the market’s surface. The Catastrophic Stop Model remains above its sell threshold, but weakening stock and high-yield bond participation warrant caution. Strong earnings revisions and AI investment support equities, while pessimistic sentiment and oversold conditions offer rebound potential. Credit spreads have not confirmed widespread financial stress. However, higher Treasury yields, rising bond volatility and persistent inflation complicate the outlook. Economic activity continues expanding, but hiring is slowing. The backdrop favors quality bonds with controlled maturity exposure. Improving breadth, stabilizing yields and upcoming economic releases will help determine whether market conditions strengthen or deteriorate further.
For more details on each sector and current model levels, please visit our research page at https://dayhagan.com/research.
This strategy uses measures of price, valuation, economic trends, liquidity, and market sentiment to make objective, rational, and emotion-free decisions about how much capital to place at risk and where to allocate it.
If you would like to discuss any of the above or our approach to investing in more detail, please don’t hesitate to schedule a call or webinar. Please call Tyler Hagan at 941-330-1702 to arrange a convenient time.
Sincerely,
Donald L. Hagan, CFA
Chief Investment Strategist, Partner, Co-Founder
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend model histories; they should be considered hypothetical. All Rights Reserved. © Copyright 2026 Day Hagan Asset Management. Data sources: Day Hagan Asset Management, 3Fourteen Research, J.P. Morgan, Goldman Sachs, Barchart, StreetStats, Atlanta Fed, St. Louis Fed, Koyfin, Yardeni, MarketEar, S&P Global, SPDR, FactSet.
Disclosures
Disclosure: The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses. Investing involves risks, including loss of principal.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise, and bonds are subject to availability and changes in price. Bond yields are subject to change. Corporate bonds are considered higher risk than government bonds but normally offer a higher yield and are subject to market, interest, and credit risk.
References to markets, asset classes, and sectors, are generally regarding the corresponding market index. Indexes are unmanaged statistical composites and cannot be invested in directly. Index performance is not indicative of the performance of any investment and does not reflect fees, expenses, or sales charges.
Data and analysis are provided “as is” without warranty of any kind, either express or implied. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. The materials may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates or market returns, and proposed or expected portfolio composition.
All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
There is no guarantee that any investment strategy will achieve its objectives, generate dividends, or avoid losses.
All hypothetical results are presented for illustrative purposes only. Back testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling, or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
Definitions
S&P 500 Index—An unmanaged composite of 500 large-cap companies, widely used by professional investors as a performance benchmark for large-cap stocks.
S&P 500 Total Return Index – An unmanaged composite of 500 large capitalization companies. Professional investors widely use this index as a performance benchmark for large-cap stocks. This index assumes reinvestment of dividends.
Russell 3000: The Russell 3000 Index measures the performance of approximately 3,000 of the largest U.S. publicly traded companies, representing about 98% of the investable U.S. equity market.
AAII Sentiment Survey — A weekly survey measuring whether individual investors expect stocks to rise, fall, or remain unchanged over the next six months.
Backwardation — A futures-market structure in which near-term commodity prices exceed longer-dated prices, often indicating tight current supplies.
Benchmark Equity Allocation — The normal percentage of a portfolio assigned to stocks based on its investment objective and risk profile.
Breadth — The degree to which market gains or losses are shared across individual stocks. Broad participation generally strengthens a market trend.
Bull-Bear Spread — The percentage of bullish investors minus the percentage of bearish investors.
Catastrophic Stop Model — Day Hagan’s risk-management model designed to identify periods when major market deterioration may warrant reducing equity exposure.
CDS, or Credit Default Swap — A market-based measure of the perceived risk that a borrower will default. Rising CDS costs generally indicate increasing credit concern.
Contrarian Buy Signal — A signal suggesting widespread pessimism may have become excessive, potentially creating a buying opportunity.
Contrarian Sell Signal — A warning that optimism, risk-taking, or positioning may have become excessive, increasing vulnerability to disappointment.
Daily Market Sentiment Composite — Day Hagan’s 0–100 measure combining multiple indicators of investor psychology. Readings below 30 indicate excessive pessimism, while readings above 70 indicate excessive optimism.
DBMF — The iMGP DBi Managed Futures Strategy ETF, used here as a proxy for positioning among systematic, trend-following strategies.
Drawdown — The percentage decline from an investment’s previous peak to its subsequent low.
Earnings Revisions — Changes analysts make to company profit estimates. Rising estimates are generally supportive of stock prices.
Federal Funds Rate — The Federal Reserve’s primary short-term policy interest rate.
FOMC — The Federal Open Market Committee, the Federal Reserve group responsible for setting monetary policy and interest rates.
Forward Earnings — Analysts’ estimates of company profits over a future period, commonly the next 12 months.
Forward Earnings Growth Rate — The expected percentage increase in future corporate earnings compared with the prior comparable period.
Forward P/E Ratio — A stock’s price divided by expected earnings over the next 12 months. Higher readings generally indicate more demanding valuations.
Magnificent Seven — Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla.
Maximum Drawdown — The largest peak-to-trough decline experienced during a specified period.
OAS, or Option-Adjusted Spread — The additional yield a bond provides over a comparable Treasury after adjusting for embedded options. Wider spreads generally indicate greater perceived credit risk.
Overbought — A condition in which prices have risen rapidly and may be vulnerable to a pause or pullback.
Oversold — A condition in which prices have fallen rapidly and may be positioned for a rebound.
PEG Ratio — The price-to-earnings ratio divided by expected long-term earnings growth. A lower ratio may indicate a more attractive valuation relative to anticipated growth.
Risk-Off Signal — An indication that market conditions have deteriorated enough to favor reducing exposure to riskier assets.
RSI, or Relative Strength Index — A momentum indicator ranging from 0 to 100. Readings above 70 commonly indicate overbought conditions, while readings below 30 indicate oversold conditions.
Systematic Investors — Strategies that adjust exposure using predefined rules based on trends, volatility, momentum, or other quantitative signals.
VIX — A market-based measure of expected S&P 500 volatility over the next 30 days, sometimes called the market’s fear gauge.
Volatility-Targeting Strategy — A rules-based strategy that generally reduces equity exposure when volatility rises and increases exposure when volatility falls.
WTI — West Texas Intermediate, a major U.S. crude-oil pricing benchmark.
WTI Forward Curve — The series of prices for WTI crude-oil futures across different expiration dates, reflecting supply, demand, storage, and market expectations.
Communication Services sector: The Communication Services Sector includes telecom and media & entertainment companies, including producers of interactive gaming products and companies engaged in content and information creation or distribution through proprietary platforms.
Consumer Discretionary sector: The Consumer Discretionary sector's manufacturing segment includes automobiles & components, household durable goods, leisure products, and textiles & apparel. The services segment includes hotels, restaurants, and other leisure facilities. It also includes distributors and retailers of consumer discretionary products.
Consumer Staples sector: The Consumer Staples sector includes manufacturers and distributors of food, beverages, and tobacco, as well as producers of non-durable household goods and personal products. It also includes distributors and retailers of consumer staples, including food & drug retailers.
Energy sector: The Energy sector includes companies that operate in exploration & production, refining & marketing, and storage & transportation of oil & gas, as well as coal & consumable fuels. It also includes companies that offer oil & gas equipment and services.
Financials sector: The Financials sector encompasses banking, financial services, consumer finance, capital markets, and insurance. It also includes Financial Exchanges & Data and Mortgage REITs.
Fixed Income sector: The Fixed Income sector includes investment securities that pay investors fixed interest payments until maturity. Designed for income generation and capital preservation, this sector includes government, corporate, and municipal bonds, as well as certificates of deposit (CDs).
Health Care sector: The Health Care sector includes health care providers & services, health care equipment & supplies, and health care technology companies. It also includes companies involved in the research, development, production, and marketing of pharmaceuticals and biotechnology products.
Industrials sector: The Industrials sector includes aerospace & defense, building products, electrical equipment, machinery, and companies that offer construction & engineering services. It also includes providers of commercial & professional services, including printing, environmental & facilities services, office services & supplies, security & alarm services, human resources & employment services, and research & consulting services. It also includes companies that provide transportation services.
Information Technology sector: The Information Technology sector includes software and information technology services, manufacturers and distributors of technology hardware & equipment, such as communications equipment, cellular phones, computers & peripherals, electronic equipment and related instruments, and semiconductors and related equipment & materials.
Materials sector: The Materials sector includes chemicals, construction materials, forest products, glass, paper and related packaging products, and metals, minerals, and mining companies, including steel producers.
Real Estate sector: The Real Estate sector includes companies engaged in real estate development and operation. It also includes companies offering real estate-related services and Equity Real Estate Investment Trusts (REITs).
Day Hagan Asset Management
1000 S. Tamiami Trail, Sarasota, FL 34236
Toll-Free: (800) 594-7930
Office Phone: (941) 330-1702
Websites:https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management