Day Hagan Catastrophic Stop Update October 26, 2026
A downloadable PDF copy of the Article:
Summary
We remain invested, but selective as market support weakens. The Catastrophic Stop Model fell to 45.45%, with reduced exposure fell below 40% for two consecutive days. Strong earnings, excessive pessimism, and rotation beyond Technology provide support, while softer breadth and slowing earnings upgrades warrant caution. We favor companies generating dependable cash flow and high-quality bonds with controlled interest-rate exposure. Fed guidance, inflation data, and election-related fiscal uncertainty will help determine whether conditions improve or require further defense.
The Day Hagan Catastrophic Stop Model declined to 45.45% from 59.09% last week as three indicators weakened. The Baltic Dry Index factor turned negative, volume-weighted supply narrowly overtook demand within the Russell 3000, and equity breadth returned to negative territory. Sentiment offered a partial counterbalance, reaching excessive pessimism that can support stocks from a contrarian perspective. The model continues to favor remaining invested, but its lower reading signals a thinner margin of support and warrants close attention to further deterioration.
Figure 1: The model remains constructive, although its margin of safety is still narrow. A reading below 40% for two consecutive days would trigger a sell signal and call for reduced equity exposure or higher cash levels.
Note: Hypothetical and historical past performance is not indicative of future results. There can be no assurance that any investment or strategy will achieve its objectives or avoid substantial losses or have comparable results. This information is provided for illustrative purposes only and is not a prediction, projection or guarantee of future performance. Hypothetical results do not reflect actual trading, were derived using the benefit of hindsight, and may not reflect material economic and market events. Actual results vary and depend on many factors and subject to risk and uncertainties.
Shipping momentum has weakened, adding a caution signal to our market outlook. The Baltic Dry Index measures rates for transporting commodities such as iron ore, coal, and grain. Its short-term trend has slipped below its longer-term average as cargo demand trails available shipping capacity. War-related insurance costs and disruptions complicate the picture, but do not establish that this signal is misleading. We are monitoring it alongside market breadth and other economic indicators for confirmation of broader weakness.
Figure 2: Shipping momentum has weakened. This is a caution flag.
Selling pressure has narrowly overtaken buying demand across the Russell 3000, signaling weaker support for stocks. Other breadth measures are mixed. Weak participation in Technology and Industrials supports caution, while stronger Health Care, Energy, and Staples breadth provides an offset. This suggests selective deterioration rather than broad capitulation, but further weakening deserves attention.
Figure 3: Equity breadth statistics are mixed, but leaning slightly negative.
Our sentiment composite has entered excessive pessimism territory, which can create opportunities as investor expectations reset lower. Elevated bearishness in the AAII survey supports that message, although options markets show caution rather than panic. Sentiment offers a potential foundation for recovery. Stronger buying demand and broader stock participation would provide more convincing confirmation.
Figure 4: Sentiment now firmly in the pessimism zone.
Breadth has recently softened slightly, with 41.9% of Russell 3000 stocks above their 50-day averages, below the 45% threshold. Participation remains above recent lows, but the recovery needs broader support to strengthen confidence in the rally.
Figure 5: Breadth still narrow = caution flag.
High-yield bond breadth remains slightly negative at −3.95, but above the −10 warning threshold. Credit markets show some softness without signaling severe stress, providing a partial offset to the recent deterioration in equity breadth.
Figure 6: High-yield breadth improving as yields retreat.
Credit spreads have widened modestly but remain below historical averages, including high yield excluding Energy. Bond investors are demanding somewhat more compensation for risk, yet these readings do not indicate widespread corporate financial stress.
Figure 7: U.S. Credit spreads (OAS) still relatively tight.
The scorecard’s 4.25 reading supports maintaining equity exposure with restraint. Strong earnings and improving participation provide reasons to stay invested, while inflation, policy uncertainty, and wider credit spreads argue against aggressively adding risk. We favor selective exposure to companies delivering earnings and cash flow, with the stop model guiding any broader reduction.
Figure 8: S&P 500 Sector Fundamentals and Technicals. Technical shading: green = strong; yellow = neutral/mixed; red = weak.
Portfolio Outlook
Sector trends favor selective equity exposure. Energy, Health Care, Staples, and Materials remain above both moving averages, while Technology’s short-term momentum has weakened. The S&P 500’s longer-term uptrend remains intact despite near-term softness.
Figure 9: S&P 500 Sector Fundamentals and Technicals. Technical shading: green = strong; yellow = neutral/mixed; red = weak. ChartExchange daily closes and FactSet. YTD exclude distributions. MA = simple average. RSI uses Wilder smoothing.
Sector Weekly Update:
For the week ended Friday, October 23, 2026, the S&P 500 declined 0.47%, the Nasdaq Composite fell 0.71%, and the Dow gained 0.41%. The modest index changes concealed a more interesting story. Eight of the eleven sector ETFs advanced, led by Energy, Health Care, and Real Estate. Communication Services suffered the largest decline. We view that combination as evidence of investors becoming more selective, with opportunities emerging beyond the companies that dominate the major indexes.
Third-quarter earnings remain supportive, but beating expectations is providing less cushion. FactSet’s October 23 Earnings Insight showed blended S&P 500 earnings growth of 29.5%, with 24% of companies reporting. Although 83% exceeded earnings estimates, aggregate earnings were only 2.1% above expectations, compared with a five-year average of 7.5%. With 179 companies scheduled to report this week, the next test is whether management teams can translate strong demand into cash flow while keeping spending under control.
Consumer Discretionary gained 0.57%. A 1.66% decline on Friday trimmed the week’s advance, underscoring how quickly confidence can change. Our focus remains on the quality of consumer demand. Retailers, automakers, and travel companies need to demonstrate that sales can grow without increasingly expensive promotions.
Consumer Staples gained 0.73%. Procter & Gamble reported 4% organic sales growth but only 1% growth in core earnings per share. Everyday purchases are supporting sales, although converting that demand into faster profit growth remains challenging.
Communication Services declined 4.36%, the weakest sector. Meta illustrated why investors are scrutinizing the cost of growth. Revenue increased 26%, but capital expenditures, including finance-lease principal payments, reached $34.91 billion, and free cash flow was negative $2.12 billion. How quickly will today’s enormous spending produce additional cash for shareholders?
Energy gained 1.60%, leading the sectors. FactSet’s blended third-quarter earnings-growth estimate reached 136%, supported by higher oil prices and comparisons with weaker year-earlier profits. That is a powerful earnings backdrop, but it does not eliminate commodity risk.
Financials gained 0.68%. American Express reported 9% revenue growth and 13% growth in adjusted earnings per share, providing evidence that its customer base continued to spend. That is encouraging, although affluent cardholders do not represent every household.
Health Care gained 1.45%, continuing its relative strength. FactSet projected a 1.2% sector earnings decline, but growth would be 9.4% excluding pharmaceuticals. The headline therefore masks considerable differences among businesses. We see greater value in identifying improving company fundamentals than in treating the entire sector as a single defensive trade.
Industrials declined 1.87%, despite encouraging results in parts of the sector. CSX reported 5% higher freight volume and 12% revenue growth. Earnings per share increased 30% compared with the prior year’s adjusted result. Moving more freight provides a tangible sign of activity.
Information Technology declined 0.13%, a much smaller loss than the previous week. Lam Research reported record quarterly revenue of $8.22 billion, up 22% from the preceding quarter, illustrating that substantial AI-related business activity continues. Our focus is the durability of that spending. Suppliers need customers whose projects can be financed and ultimately generate adequate economic returns.
Materials gained 0.77%. FactSet projected 30% sector earnings growth, with metals and mining, packaging, and chemicals contributing. Construction materials remained an exception, with declining profits expected. These differences matter. We are looking for improving shipment volumes and margins, particularly where higher energy and transportation costs could consume the benefit of stronger selling prices.
Real Estate gained 0.97%, placing third among the sector ETFs. An occupied building can still disappoint shareholders if refinancing absorbs its rental income. We emphasize manageable debt maturities, reliable tenants, and leases that allow cash flow to improve as costs rise.
Utilities gained 0.83%. For this sector, the AI investment debate creates a practical question about when projected electricity demand becomes paying customers. We want to see firm commitments, credible construction schedules, and a clear process for recovering investment costs.
Note. Index figures are weekly price returns. Sector figures are published closing-price returns for the 11 Select Sector SPDR ETFs from October 16 through October 23, 2026. They exclude distributions and may differ from dividend-adjusted ETF returns or corresponding S&P 500 sector index returns. Earnings estimates reflect FactSet’s October 23 update and combine reported results with estimates for companies yet to report.
Figure 10: Sector Relative Strength vs. S&P 500.
Participation favors Energy, Health Care, Staples, and Materials, where most stocks trade above both moving averages. Utilities’ rebound lacks longer-term confirmation, while weak Communication Services breadth shows the market’s recovery remains uneven across sectors.
Figure 11: Breadth improvement happening in previously ignored sectors.
Volatility-targeting equity exposure is elevated, but not at levels seen around previous extremes. Elevated positioning also increases vulnerability to automatic selling if volatility rises, potentially amplifying a market pullback.
Figure 12: Vol-targeting funds’ exposure remains over +1 SD. Another yellow flag (caution).
DBMF’s S&P 500 exposure has fallen to 25.6% from roughly 45%, signaling reduced equity participation while remaining net long. This reflects a more cautious stance, but does not establish that stocks face further declines.
Figure 13: Positioning indicators remain mixed, but the overall message remains “high neutral.”
Earnings expectations are still rising, but upgrades are losing momentum across most sectors. The S&P 500’s forward earnings estimate increased 8% over 63 days, below its earlier pace. Communication Services has turned negative, while Energy is reaccelerating. This signals fading earnings support at the margin, rather than an outright decline in profits.
Figure 14: Earnings continue to support equities.
Seasonal patterns suggest tailwinds for the remainder of the year.
Figure 15: Updated S&P 500 cycle composite for 2026 and 2027.
The scorecard’s 3.75 reading calls for measured exposure. Inflation, heavy government borrowing, and widening credit spreads remain constraints. Spreading maturities helps capture attractive yields while limiting sensitivity to rising rates and preserving flexibility as conditions change.
Figure 16: The scorecard supports selective bond exposure, emphasizing high credit quality and manageable interest-rate risk. Scores are equal-weight research judgment. Treasury yields Oct. 23. HY Spreads: Oct 22.
The recent pullback in Treasury yields lifted existing bond prices and eased valuation pressure on equities by increasing the present value of future earnings. Lower yields also offer some relief for financing costs. However, rates remain elevated, so the decline provides modest support without removing a significant constraint on stocks and bonds.
Figure 17: Rates have pulled back slightly.
Markets assign roughly a 91% probability that the Fed holds rates at 3.75%–4.00% on October 28, while still anticipating a December increase. Strong consumer spending and AI investment argue against easing, while slower hiring and tighter financial conditions support a pause. Recent New York Fed survey results showed rising inflation expectations, reinforcing policymakers’ caution. The key message will be whether officials view this pause as time to assess September’s hike before potentially tightening again.
Figure 18: Investors expect the Fed to hold steady this Wednesday.
U.S. Economic Releases:
Last week’s data showed continued expansion, with manufacturing and services surveys comfortably above 50, despite weaker housing starts and pending sales. Employment remained stable, as low jobless claims offset slower private hiring. Inflation expectations stayed elevated at 4.7%, suggesting price concerns persist. Overall, growth remains intact, but housing weakness and inflation complicate policy.
This week, watch the Fed’s guidance for clues about another hike, then GDP and consumer spending for growth strength. Core PCE inflation, employment costs, and jobless claims will clarify whether price pressures are easing without weakening employment.
Figure 19: Economic release calendar. Source: Forexfactory.com
Midterm years have historically been uneven for stocks. From 1931 through 2025, the S&P 500 averaged a 4.7% calendar-year price gain in midterm years, versus 9.6% in other years. The average midterm path was weakest around September. The picture improved after voting: the chart shows an average 14.8% price gain in the 12 months following Election Day since 1950. These are historical averages, not a forecast. Economic conditions, earnings, and interest rates still shape each cycle.
Figure 20: Whether a midterm year or not, equities have tended to find a bottom during the September/October period.
A Democratic congressional takeover could potentially increase conflict with the White House over spending, taxes, immigration, and regulation. Divided government would constrain major policy changes, but budget standoffs and fiscal uncertainty could unsettle investors. If domestic and foreign investors lose confidence in Washington’s ability to manage debt and govern predictably, we believe higher Treasury yields and lower stock valuations could follow. The equity risk is a higher premium for policy uncertainty, especially with inflation and borrowing costs already elevated.
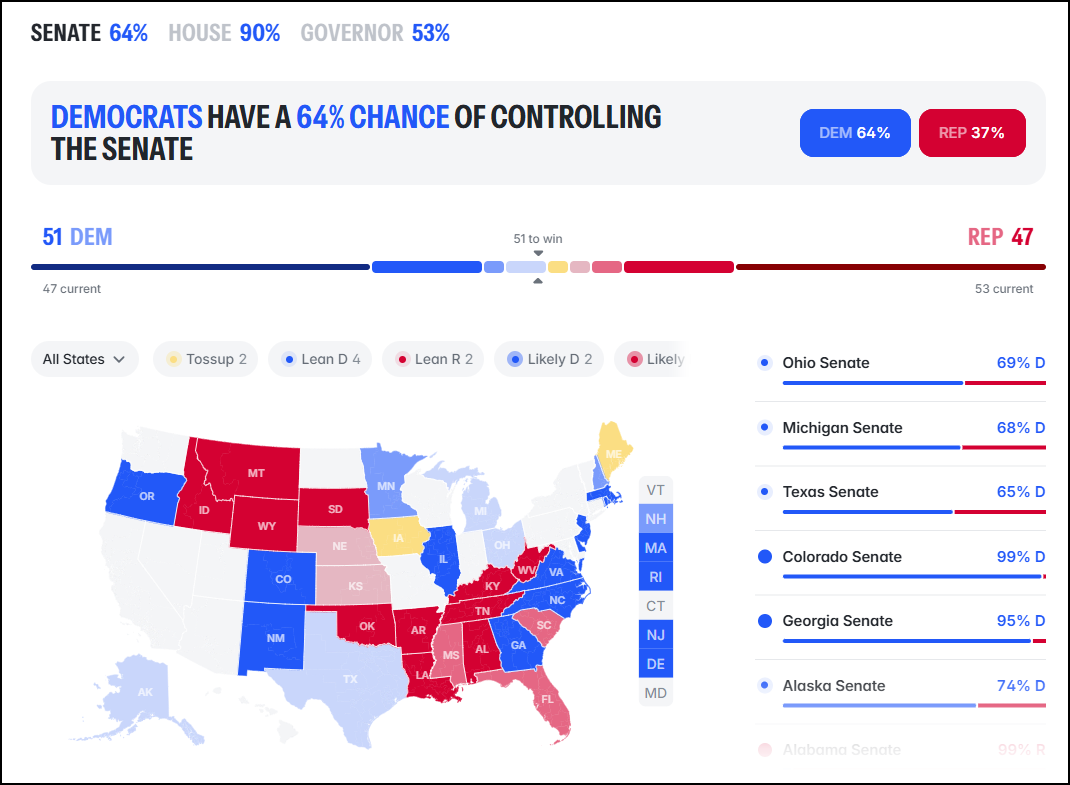
Figure 21: History shows that following elections, markets tend to do well. Is this time different? It looks to us like investors are already positioning for potential disruptions, which can be positive.
Source: Polymarket.us, as of October 26, 2026. Probabilities reflect prediction-market trading activity and participants' expectations regarding potential election outcomes. These probabilities are subject to change and may be influenced by market sentiment, trading volume, and liquidity. They do not represent statistically determined probabilities or guarantees of actual election results.
Bottom Line
We remain invested, but selective as market support weakens. The Catastrophic Stop Model fell to 45.45%, with reduced exposure triggered below 40% for two consecutive days. Strong earnings, excessive pessimism, and rotation beyond Technology provide support, while softer breadth and slowing earnings upgrades warrant caution. We favor companies generating dependable cash flow and high-quality bonds with controlled interest-rate exposure. Fed guidance, inflation data, and election-related fiscal uncertainty will help determine whether conditions improve or require further defense.
For more details on each sector and current model levels, please visit our research page at https://dayhagan.com/research.
This strategy uses measures of price, valuation, economic trends, liquidity, and market sentiment to make objective, rational, and emotion-free decisions about how much capital to place at risk and where to allocate it.
If you would like to discuss any of the above or our approach to investing in more detail, please don’t hesitate to schedule a call or webinar. Please call Tyler Hagan at 941-330-1702 to arrange a convenient time.
Sincerely,
Donald L. Hagan, CFA
Chief Investment Strategist, Partner, Co-Founder
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend model histories; they should be considered hypothetical. All Rights Reserved. © Copyright 2026 Day Hagan Asset Management. Data sources: Day Hagan Asset Management, 3Fourteen Research, J.P. Morgan, Goldman Sachs, Barchart, StreetStats, Atlanta Fed, St. Louis Fed, Koyfin, Yardeni, MarketEar, S&P Global, SPDR, FactSet.
Disclosures
Disclosure: The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses. Investing involves risks, including loss of principal.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise, and bonds are subject to availability and changes in price. Bond yields are subject to change. Corporate bonds are considered higher risk than government bonds but normally offer a higher yield and are subject to market, interest, and credit risk.
References to markets, asset classes, and sectors, are generally regarding the corresponding market index. Indexes are unmanaged statistical composites and cannot be invested in directly. Index performance is not indicative of the performance of any investment and does not reflect fees, expenses, or sales charges.
Data and analysis are provided “as is” without warranty of any kind, either express or implied. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. The materials may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates or market returns, and proposed or expected portfolio composition.
All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
There is no guarantee that any investment strategy will achieve its objectives, generate dividends, or avoid losses.
All hypothetical results are presented for illustrative purposes only. Back testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling, or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
Definitions
S&P 500 Index—An unmanaged composite of 500 large-cap companies, widely used by professional investors as a performance benchmark for large-cap stocks.
S&P 500 Total Return Index – An unmanaged composite of 500 large capitalization companies. Professional investors widely use this index as a performance benchmark for large-cap stocks. This index assumes reinvestment of dividends.
Russell 3000: The Russell 3000 Index measures the performance of approximately 3,000 of the largest U.S. publicly traded companies, representing about 98% of the investable U.S. equity market.
AAII Sentiment Survey — A weekly survey measuring whether individual investors expect stocks to rise, fall, or remain unchanged over the next six months.
Backwardation — A futures-market structure in which near-term commodity prices exceed longer-dated prices, often indicating tight current supplies.
Benchmark Equity Allocation — The normal percentage of a portfolio assigned to stocks based on its investment objective and risk profile.
Breadth — The degree to which market gains or losses are shared across individual stocks. Broad participation generally strengthens a market trend.
Bull-Bear Spread — The percentage of bullish investors minus the percentage of bearish investors.
Catastrophic Stop Model — Day Hagan’s risk-management model designed to identify periods when major market deterioration may warrant reducing equity exposure.
CDS, or Credit Default Swap — A market-based measure of the perceived risk that a borrower will default. Rising CDS costs generally indicate increasing credit concern.
Contrarian Buy Signal — A signal suggesting widespread pessimism may have become excessive, potentially creating a buying opportunity.
Contrarian Sell Signal — A warning that optimism, risk-taking, or positioning may have become excessive, increasing vulnerability to disappointment.
Daily Market Sentiment Composite — Day Hagan’s 0–100 measure combining multiple indicators of investor psychology. Readings below 30 indicate excessive pessimism, while readings above 70 indicate excessive optimism.
DBMF — The iMGP DBi Managed Futures Strategy ETF, used here as a proxy for positioning among systematic, trend-following strategies.
Drawdown — The percentage decline from an investment’s previous peak to its subsequent low.
Earnings Revisions — Changes analysts make to company profit estimates. Rising estimates are generally supportive of stock prices.
Federal Funds Rate — The Federal Reserve’s primary short-term policy interest rate.
FOMC — The Federal Open Market Committee, the Federal Reserve group responsible for setting monetary policy and interest rates.
Forward Earnings — Analysts’ estimates of company profits over a future period, commonly the next 12 months.
Forward Earnings Growth Rate — The expected percentage increase in future corporate earnings compared with the prior comparable period.
Forward P/E Ratio — A stock’s price divided by expected earnings over the next 12 months. Higher readings generally indicate more demanding valuations.
Magnificent Seven — Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla.
Maximum Drawdown — The largest peak-to-trough decline experienced during a specified period.
OAS, or Option-Adjusted Spread — The additional yield a bond provides over a comparable Treasury after adjusting for embedded options. Wider spreads generally indicate greater perceived credit risk.
Overbought — A condition in which prices have risen rapidly and may be vulnerable to a pause or pullback.
Oversold — A condition in which prices have fallen rapidly and may be positioned for a rebound.
PEG Ratio — The price-to-earnings ratio divided by expected long-term earnings growth. A lower ratio may indicate a more attractive valuation relative to anticipated growth.
Risk-Off Signal — An indication that market conditions have deteriorated enough to favor reducing exposure to riskier assets.
RSI, or Relative Strength Index — A momentum indicator ranging from 0 to 100. Readings above 70 commonly indicate overbought conditions, while readings below 30 indicate oversold conditions.
Systematic Investors — Strategies that adjust exposure using predefined rules based on trends, volatility, momentum, or other quantitative signals.
VIX — A market-based measure of expected S&P 500 volatility over the next 30 days, sometimes called the market’s fear gauge.
Volatility-Targeting Strategy — A rules-based strategy that generally reduces equity exposure when volatility rises and increases exposure when volatility falls.
WTI — West Texas Intermediate, a major U.S. crude-oil pricing benchmark.
WTI Forward Curve — The series of prices for WTI crude-oil futures across different expiration dates, reflecting supply, demand, storage, and market expectations.
Day Hagan Asset Management
1000 S. Tamiami Trail, Sarasota, FL 34236
Toll-Free: (800) 594-7930
Office Phone: (941) 330-1702
Websites:https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management