Day Hagan Catastrophic Stop Update October 19, 2026
A downloadable PDF copy of the Article:
Summary
The evidence continues to support remaining invested, with caution. The Catastrophic Stop Model improved to 59.09%, and the high-yield bond breadth factor returned to a buy signal. However, Technology’s sharp decline shows how quickly strong earnings expectations can collide with concerns about valuations and financing. Strength in several other sectors provides a counterweight. Treasury yields eased, but renewed inflation pressure limits confidence in further relief. We are watching whether improving participation and corporate results can support a more durable advance.
The Day Hagan Catastrophic Stop Model rose to 59.09% from 54.55% last week, returning to its level from two weeks ago. High Yield Bond Breadth also improved, moving back to a buy signal, though it continues to fluctuate around neutral. The message remains to stay invested while monitoring for renewed deterioration.
Figure 1: The model remains constructive, although its margin of safety is still narrow. A reading below 40% for two consecutive days would trigger a sell signal and call for reduced equity exposure or higher cash levels.
Hypothetical and historical past performance is not indicative of future results. There can be no assurance that any investment or strategy will achieve its objectives or avoid substantial losses or have comparable results. This information is provided for illustrative purposes only and is not a prediction, projection or guarantee of future performance. Hypothetical results do not reflect actual trading, were derived using the benefit of hindsight, and may not reflect material economic and market events. Actual results vary and depend on many factors and subject to risk and uncertainties.
More S&P 500 stocks have recently slipped well below their five-year highs, signaling broader underlying weakness. Currently, 393 are down at least 10%, including 271 down 20% or more. However, the number down 50% remains comparatively contained at 57, suggesting widespread corrections without the deep damage seen during major crises.
Figure 2: 393 stocks within the current S&P 500 are 10% or more below their five-year closing highs.
Sentiment has fallen sharply from recent optimism, although it has edged back up to 36.54 from near the pessimism threshold of 30. With the S&P 500 still near its highs, investors appear cautious rather than euphoric. That reduces concerns about excessive optimism, but does not guarantee a market rebound.
Figure 3: Sentiment continues to lean pessimistic.
Only 29.18% of Russell 3000 stocks trade above their 50-day averages, down sharply from recent levels. Breadth is oversold despite the S&P 500’s elevated level, highlighting narrow leadership and potential for a rebound.
Figure 4: Breadth still narrow = caution flag.
High-yield bond breadth has rebounded sharply to +2.26, recovering above both warning thresholds. This suggests easing selling pressure and improving credit participation, offering an encouraging counterpoint to weak stock-market breadth.
Figure 5: High-yield breadth improving.
Credit spreads have edged higher but remain below historical averages, suggesting limited concern about corporate defaults. Credit markets are not signaling broad financial stress, although narrow spreads offer less protection against adverse surprises.
Figure 6: U.S. Credit spreads (OAS) still relatively tight.
The scorecard’s 4.08 out of 10 reflects a mixed backdrop with more constraints than support. Strong earnings growth and AI spending provide support, while lower Treasury yields and improving credit breadth offer some relief. However, renewed inflation, slower hiring and weak stock participation limit confidence in a broader advance. Earnings results are encouraging but still early. The message is to remain invested and selective, while watching whether improving credit conditions translate into stronger equity breadth.
Figure 7: Have we seen the worst in credit conditions for the time being?
Portfolio Outlook
Leadership is uneven. Energy leads year to date, while Staples and Health Care show stronger near-term trends. Technology remains a major annual winner but has weakened toward oversold levels. Only four sectors exceed their 50-day averages, suggesting strong headline earnings have yet to translate into broad market strength.
Figure 8: S&P 500 Sector Fundamentals and Technicals. Technical shading: green = strong; yellow = neutral/mixed; red = weak.
Sector Weekly Update:
For the week ended Friday, October 16, 2026, the S&P 500 declined 1.9% on a price-return basis, the Nasdaq Composite fell 4.5%, and the Dow gained 0.7%. Technology weakness drove the major growth indexes lower as investors questioned the financing and eventual returns from AI infrastructure spending. However, gains across seven sector ETFs showed that the selling was not uniform. Consumer Staples, Energy, and Health Care led, while Information Technology was the weakest sector.
Third-quarter earnings remain supportive, but expectations are high. FactSet’s October 16 Earnings Insight showed blended S&P 500 earnings growth of 29.0%, down from 29.4% the previous week. Only 9% of companies had reported. Although 84% exceeded earnings estimates, the aggregate beat was just 2.6%, below the five-year average of 7.5%. Strong growth alone may not be enough when investors already expect exceptional results.
Consumer Discretionary declined 0.35%. The modest weekly loss masked the importance of upcoming earnings guidance. Recent bank commentary indicated that consumer spending and credit quality remained relatively steady. Our focus is whether retailers, automakers, and travel businesses can maintain sales without heavier discounting, particularly as energy and borrowing costs compete for household dollars.
Consumer Staples gained 5.02%, leading all sectors. The advance was consistent with investors seeking more predictable demand as Technology weakened. In its recent quarterly update, PepsiCo reported 5.6% revenue growth and 3.1% organic revenue growth, including organic volume gains across global foods and beverages.
Communication Services declined 0.05%, essentially unchanged. FactSet placed the sector among the leaders in expected third-quarter earnings growth. The next test is whether advertising and platform revenues can support expanding AI expenditures while preserving cash generation.
Energy gained 4.86%. Earnings expectations strengthened alongside the sector’s advance. FactSet identified upward revisions to Energy earnings and revenue estimates as an important positive development during the week. Higher commodity prices can improve producer cash flow, but our focus remains on capital discipline, production costs, and how much cash reaches shareholders.
Financials gained 1.44%. Bank results were mixed. JPMorgan and Bank of America missed profit expectations, while other major banks exceeded forecasts. Equity trading was stronger than fixed-income trading, and deal activity faced delays. FactSet’s sector earnings-growth estimate remained 3.0%. Higher rates can support interest income, but funding costs, credit quality, and capital-markets activity still determine the overall outcome.
Health Care gained 3.45%, despite a less favorable earnings backdrop. FactSet identified downward earnings revisions as the largest drag on the week’s overall earnings-growth estimate. Health Care was also the only sector expected to report declining profits. The divergence reinforces the importance of separating defensive stock-market demand from improving business fundamentals.
Industrials declined 0.88%. The sector held up considerably better than Technology, but upcoming reports still need to demonstrate that investment spending is translating into profitable deliveries. We are watching order cancellations, backlog conversion, pricing, and cash flow. Higher revenue is more valuable when companies can deliver it without disproportionate increases in inventory, labor, and financing costs.
Information Technology declined 7.70%. Strong operating results offered limited protection against concerns about AI spending and financing. Taiwan Semiconductor and ASML reported strong earnings and guidance, yet their shares fell amid the broader semiconductor selloff. The investment question is increasingly whether future cash flows justify both current valuations and the capital being committed to new capacity.
Materials gained 3.01%. FactSet included Materials among the sectors leading expected earnings growth. That provides a more constructive backdrop, although individual businesses face different commodity prices and end-market demand. We want earnings reports to show improving volumes and margins, with particular attention to whether higher energy and transportation expenses offset stronger selling prices.
Real Estate gained 1.32%. The weekly decline in Treasury yields provided a more favorable financing backdrop. Upcoming earnings commentary should help clarify whether occupancy, rental growth, and property cash flow can absorb refinancing costs. We remain focused on debt maturities and access to capital, particularly where leases reset more slowly than financing expenses.
Utilities gained 1.93%. FactSet’s recent sector preview emphasized data-center construction as an important long-term driver of electricity demand. The earnings opportunity depends on how quickly that demand materializes and how investment costs are recovered.
Note. Index figures are weekly price returns. Sector figures are published closing-price returns for the 11 Select Sector SPDR ETFs from October 9 through October 16, 2026. They exclude distributions and may differ from dividend-adjusted ETF returns or corresponding S&P 500 sector index returns. Earnings estimates reflect FactSet’s October 16 update and combine reported results with estimates for companies yet to report.
Figure 9: Sector Relative Strength vs. S&P 500
Energy, Health Care and Staples show broader strength among individual stocks, while Technology’s participation has weakened. Utilities’ rebound is mainly short term, with just 16% above their 200-day averages. Recent improvement in several sectors is encouraging, but overall leadership remains uneven.
Figure 10: Breadth improvement happening in previously ignored sectors.
Volatility-targeting equity exposure has risen well above its five-year average, suggesting systematic buying has supported stocks. Elevated positioning also increases vulnerability to automatic selling if volatility rises, potentially amplifying a market pullback.
Figure 11: Vol-targeting funds’ exposure remains over +1 SD. Another yellow flag (caution).
DBMF’s S&P 500 exposure has climbed to 45.96%, near the upper end of its recent range. This broadly confirms the previous chart’s message of increased systematic equity exposure, although the strategies differ. Both suggest positioning has supported stocks, while leaving greater potential for selling if trends weaken or volatility rises.
Figure 12: Positioning indicators remain mixed, but the overall message remains “high neutral.”
Analysts have raised S&P 500 forward earnings estimates 8.9% over the past 63 trading days, an unusually strong pace. Every sector shows positive revisions, led by Energy and Technology. However, several sectors’ revision rates have eased from recent peaks. Earnings expectations remain supportive, even as stock-market participation has weakened.
Figure 13: Earnings continue to support equities.
Seasonal patterns suggest tailwinds for the remainder of the year.
Figure 14: Updated S&P 500 cycle composite for 2026 and 2027.
The scorecard’s 3.83 out of 10 suggests an appealing income opportunity within a challenging bond environment. Lower Treasury yields have supported prices, and improved high-yield breadth is encouraging. However, inflation, heavy Treasury supply and limited compensation for credit risk constrain the outlook. Short- and intermediate-term bonds offer income with less interest-rate sensitivity than longer maturities. The emphasis remains on credit quality and controlled maturity, rather than relying on a sustained decline in yields to generate returns.
Figure 15: Scorecard improvement.
Lower interest rates offered equities some relief last week, but were not enough to offset broader selling pressure.
Figure 16: A visual of the rise in rates.
Treasury yields remain substantially above year-ago levels despite last week’s decline. Longer maturities also yield more than a month ago, offering additional income while keeping borrowing costs elevated and bond prices sensitive to rates.
Figure 17: Selected Treasury and Mortgage rates.
The MOVE Index at 101.10 signals increased bond-market uncertainty versus summer, but remains below past crisis peaks. (It measures expected volatility, not direction, so this chart cannot quantify the probability of a major decline.)
Figure 18: The MOVE index spiked first, and now the VIX is catching up.
The VIX rose toward 20 on Friday, signaling increased expectations for stock-market swings. Concern has picked up, but remains well below past stress peaks. This suggests caution, not panic.
Figure 19: While the VIX may be catching up to MOVE, both are well below peaks that have identified previous lows.
U.S. Economic Releases:
Based on last week’s economic releases, U.S. activity remained firm while inflation pressures intensified. Retail sales rose 0.8% and industrial production increased 0.7%, both exceeding forecasts. Jobless claims remained low at 199,000, suggesting limited layoffs. Manufacturing surveys were mixed but positive, while small-business confidence softened. Spending figures are nominal, so higher prices explain some of the gain.
Inflation was the less encouraging story. Consumer prices rose 0.6% monthly, lifting annual inflation to 3.7%. Core CPI increased 0.3%, while producer and import prices jumped 1.3% and 1.1%. Together, these reports suggest continued expansion, but less room for the Fed to ease policy.
This week’s calendar should help clarify whether growth is holding up as inflation pressures build.
Housing data Monday and Tuesday will show how borrowing costs are affecting builder confidence, construction and buyer demand.
ADP employment and Thursday’s jobless claims will help distinguish slow hiring from an increase in layoffs.
Friday’s manufacturing and services PMIs are the main growth check. Watch new orders, employment and prices charged alongside the headline readings.
Consumer inflation expectations will indicate whether recent price increases are becoming embedded in household thinking.
The favorable combination would be steady activity, limited layoffs and easing price pressures.
Figure 20: Economic release calendar. Source: Forexfactory.com
Midterm years have historically been uneven for stocks. From 1931 through 2025, the S&P 500 averaged a 4.7% calendar-year price gain in midterm years, versus 9.6% in other years. The average midterm path was weakest around September. The picture improved after voting: the chart shows an average 14.8% price gain in the 12 months following Election Day since 1950. These are historical averages, not a forecast. Economic conditions, earnings, and interest rates still shape each cycle.
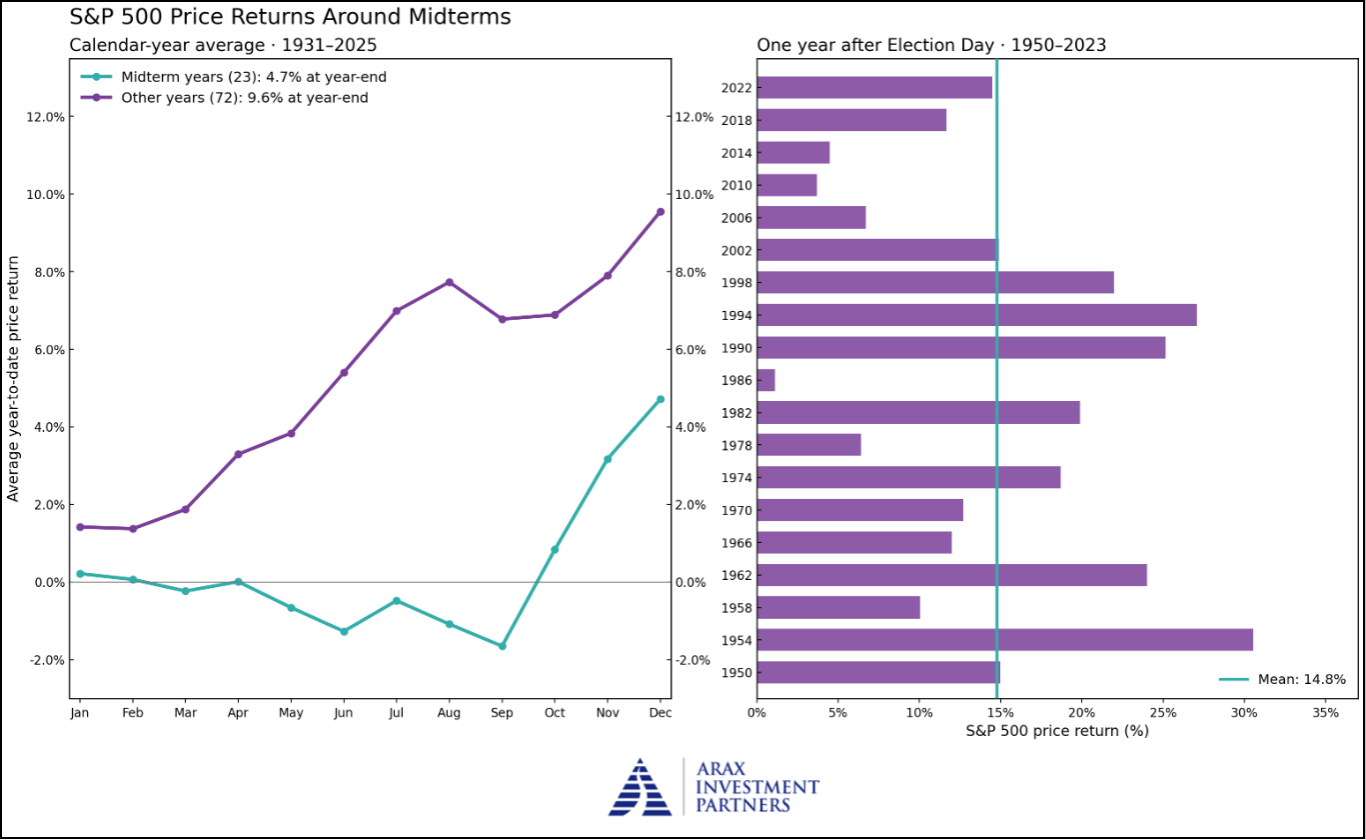
Figure 21: Whether a midterm year or not, equities have tended to find a bottom during the September/October period.
Bottom Line
Our plan is to remain invested, emphasize earnings quality and follow our risk signals. The Catastrophic Stop Model improved to 59.09%, and high-yield bond breadth returned to a buy signal, supporting continued equity exposure. Technology’s selloff reinforces the need to distinguish promising businesses from stocks priced for perfection. We are looking for dependable cash flow, credible earnings delivery and improving participation beyond the largest companies. In bonds, we favor quality and short-to-intermediate maturities to capture income while controlling rate sensitivity. If our risk model falls below 40% for two consecutive days, we will reduce equity exposure. Discipline, rather than headlines, will guide our next move.
For more details on each sector and current model levels, please visit our research page at https://dayhagan.com/research.
This strategy uses measures of price, valuation, economic trends, liquidity, and market sentiment to make objective, rational, and emotion-free decisions about how much capital to place at risk and where to allocate it.
If you would like to discuss any of the above or our approach to investing in more detail, please don’t hesitate to schedule a call or webinar. Please call Tyler Hagan at 941-330-1702 to arrange a convenient time.
Sincerely,
Donald L. Hagan, CFA
Chief Investment Strategist, Partner, Co-Founder
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend model histories; they should be considered hypothetical. All Rights Reserved. © Copyright 2026 Day Hagan Asset Management. Data sources: Day Hagan Asset Management, 3Fourteen Research, J.P. Morgan, Goldman Sachs, Barchart, StreetStats, Atlanta Fed, St. Louis Fed, Koyfin, Yardeni, MarketEar, S&P Global, SPDR, FactSet.
Disclosures
Disclosure: The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses. Investing involves risks, including loss of principal.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise, and bonds are subject to availability and changes in price. Bond yields are subject to change. Corporate bonds are considered higher risk than government bonds but normally offer a higher yield and are subject to market, interest, and credit risk.
References to markets, asset classes, and sectors, are generally regarding the corresponding market index. Indexes are unmanaged statistical composites and cannot be invested in directly. Index performance is not indicative of the performance of any investment and does not reflect fees, expenses, or sales charges.
Data and analysis are provided “as is” without warranty of any kind, either express or implied. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. The materials may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates or market returns, and proposed or expected portfolio composition.
All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
There is no guarantee that any investment strategy will achieve its objectives, generate dividends, or avoid losses.
All hypothetical results are presented for illustrative purposes only. Back testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling, or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
Definitions
S&P 500 Index—An unmanaged composite of 500 large-cap companies, widely used by professional investors as a performance benchmark for large-cap stocks.
S&P 500 Total Return Index – An unmanaged composite of 500 large capitalization companies. Professional investors widely use this index as a performance benchmark for large-cap stocks. This index assumes reinvestment of dividends.
Russell 3000: The Russell 3000 Index measures the performance of approximately 3,000 of the largest U.S. publicly traded companies, representing about 98% of the investable U.S. equity market.
AAII Sentiment Survey — A weekly survey measuring whether individual investors expect stocks to rise, fall, or remain unchanged over the next six months.
Backwardation — A futures-market structure in which near-term commodity prices exceed longer-dated prices, often indicating tight current supplies.
Benchmark Equity Allocation — The normal percentage of a portfolio assigned to stocks based on its investment objective and risk profile.
Breadth — The degree to which market gains or losses are shared across individual stocks. Broad participation generally strengthens a market trend.
Bull-Bear Spread — The percentage of bullish investors minus the percentage of bearish investors.
Catastrophic Stop Model — Day Hagan’s risk-management model designed to identify periods when major market deterioration may warrant reducing equity exposure.
CDS, or Credit Default Swap — A market-based measure of the perceived risk that a borrower will default. Rising CDS costs generally indicate increasing credit concern.
Contrarian Buy Signal — A signal suggesting widespread pessimism may have become excessive, potentially creating a buying opportunity.
Contrarian Sell Signal — A warning that optimism, risk-taking, or positioning may have become excessive, increasing vulnerability to disappointment.
Daily Market Sentiment Composite — Day Hagan’s 0–100 measure combining multiple indicators of investor psychology. Readings below 30 indicate excessive pessimism, while readings above 70 indicate excessive optimism.
DBMF — The iMGP DBi Managed Futures Strategy ETF, used here as a proxy for positioning among systematic, trend-following strategies.
Drawdown — The percentage decline from an investment’s previous peak to its subsequent low.
Earnings Revisions — Changes analysts make to company profit estimates. Rising estimates are generally supportive of stock prices.
Federal Funds Rate — The Federal Reserve’s primary short-term policy interest rate.
FOMC — The Federal Open Market Committee, the Federal Reserve group responsible for setting monetary policy and interest rates.
Forward Earnings — Analysts’ estimates of company profits over a future period, commonly the next 12 months.
Forward Earnings Growth Rate — The expected percentage increase in future corporate earnings compared with the prior comparable period.
Forward P/E Ratio — A stock’s price divided by expected earnings over the next 12 months. Higher readings generally indicate more demanding valuations.
Magnificent Seven — Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla.
Maximum Drawdown — The largest peak-to-trough decline experienced during a specified period.
OAS, or Option-Adjusted Spread — The additional yield a bond provides over a comparable Treasury after adjusting for embedded options. Wider spreads generally indicate greater perceived credit risk.
Overbought — A condition in which prices have risen rapidly and may be vulnerable to a pause or pullback.
Oversold — A condition in which prices have fallen rapidly and may be positioned for a rebound.
PEG Ratio — The price-to-earnings ratio divided by expected long-term earnings growth. A lower ratio may indicate a more attractive valuation relative to anticipated growth.
Risk-Off Signal — An indication that market conditions have deteriorated enough to favor reducing exposure to riskier assets.
RSI, or Relative Strength Index — A momentum indicator ranging from 0 to 100. Readings above 70 commonly indicate overbought conditions, while readings below 30 indicate oversold conditions.
Systematic Investors — Strategies that adjust exposure using predefined rules based on trends, volatility, momentum, or other quantitative signals.
VIX — A market-based measure of expected S&P 500 volatility over the next 30 days, sometimes called the market’s fear gauge.
Volatility-Targeting Strategy — A rules-based strategy that generally reduces equity exposure when volatility rises and increases exposure when volatility falls.
WTI — West Texas Intermediate, a major U.S. crude-oil pricing benchmark.
WTI Forward Curve— The series of prices for WTI crude-oil futures across different expiration dates, reflecting supply, demand, storage, and market expectations.
Day Hagan Asset Management
1000 S. Tamiami Trail, Sarasota, FL 34236
Toll-Free: (800) 594-7930
Office Phone: (941) 330-1702
Websites:https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management