Day Hagan Smart Sector® Fixed Income Strategy Update September 2026
A downloadable PDF copy of the Article:
Day Hagan Smart Sector® Fixed Income Strategy Update September 2026 (pdf)
Executive Summary
August delivered a useful reminder: income may help cushion a bond portfolio, but it doesn’t always offset significant price declines. Government yields rose across much of the developed world as investors reconsidered inflation, central-bank policy, fiscal borrowing, and the capital required for artificial-intelligence infrastructure. Longer-term government bonds lagged, while floating-rate and lower-quality credit generally held up better. The market rewarded current income and punished exposure whose payoff depended on a quick decline in long-term rates.
The September setup is no cleaner. The August employment report showed 162,000 new payrolls and a 4.1% unemployment rate, well above the pace markets expected. July’s PCE price index was still 3.7% above a year earlier and core PCE was 3.3%. August purchasing-manager surveys described an economy that is expanding, but also reported unusually firm input costs. That combination gives the Federal Reserve room to wait—and keeps the risk of another increase in policy rates on the table.
The yield curve reflects that debate. As of September 3, three-month bills yielded about 3.84%, two-year Treasuries 4.35%, the 10-year 4.77%, and the 30-year 5.25%. The positive slope between short and long maturities now offers more income for accepting duration, but it also embeds a larger term premium for inflation (term premium is the extra yield investors demand for holding longer-term bonds instead of short-term securities) and supply. The 10-year breakeven inflation was approximately 2.35%, while the 10-year real yield remained near 2.4%.
The Federal Reserve held its target range at 3.50% to 3.75% in July, with three members preferring an increase. Since then, officials have emphasized both the possibility of continued disinflation and the structural pressure that deficits and private capital spending may place on long-term rates. The next policy decision may move the front end, but the long end is also reflecting the dynamics of Treasury supply, energy prices, and global bond markets.
Against that backdrop, U.S. 1–3 Year, 3–10 Year, and 10+ Year Treasuries are neutral. Short-term TIPS are neutral, up from underweight. U.S. Mortgage-Backed Securities are underweight, down from overweight. U.S. Floating Rate Notes are neutral. U.S. Corporate Aggregate Bonds are underweight. U.S. High Yield is overweight. International Bonds are neutral, up from underweight, and Emerging-Market Bonds remain overweight.
The allocations are not a single forecast about the Fed. They divide the opportunity into three jobs: preserve flexibility in Treasuries and floating-rate notes, use credit selectively where income and market confirmation remain supportive, and limit broad fixed-rate exposure where trend, spread, and supply signals are unfavorable. The result is balanced duration, an emphasis on liquid income, and disciplined exposure to credit risk.
Our quantitative models reinforce that separation. Floating-rate notes have five bullish readings and no bearish readings, but their resetting coupons limit appreciation if policy eventually turns lower. High yield is evenly split, yet its income and technical trend support an overweight with an emphasis on stronger issuers. The broad U.S. Investment Grade Corporates model has only one bullish reading out of six, while global IG Corporate bonds show three bullish and two bearish signals. Emerging-market bonds have the strongest international mix at four bullish readings and one bearish reading.
This is a market for earning, not reaching. We are willing to collect income in high yield and emerging markets, but not to treat tight spreads as a substitute for underwriting. We are willing to hold duration, but not to assume that every rise in yield is automatically a buying signal. Data and market levels cited in this letter are rounded and reflect information available through September 4, 2026. The positioning remains model-driven and may change as prices, spreads, liquidity, and economic conditions evolve.
Holdings
Fixed Income Sector
US 1-3 Month T-bill
US 3-7 Year Treasury
US 10-20 Year Treasury
TIPS (short-term)
US Mortgage-Backed
US Floating Rate
US Corporate
US High Yield
International Corporate Bond
Emerging Market Bond
Outlook (relative to benchmark)
Neutral
Neutral
Neutral
Neutral
Underweight
Neutral
Underweight
Overweight
Neutral
Overweight
Position Details
U.S. TREASURIES — NEUTRAL
Treasuries begin September with income across the curve and a larger reward for moving beyond cash. On September 3, the three-month bill yielded approximately 3.84%, the two-year 4.35%, the five-year 4.52%, the 10-year 4.77%, and the 30-year 5.25%. The 10-year/three-month spread was about 93 basis points. A curve that steep is useful for reinvestment planning, but it also signals that investors want meaningful compensation for inflation, fiscal supply, and time.
The U.S. Treasury model is cautious: the technical cross, momentum, equity-market trend, and inflation-expectations signals are bearish, while the credit-default-swap input is bullish. That one defensive signal matters because long Treasuries can still rally sharply if credit deteriorates or growth weakens. It does not offset the current trend. Long duration remains vulnerable when the catalyst is inflation or increased borrowing rather than a conventional growth shock.
Recent releases argue against making an aggressive duration bet. August payrolls rose 162,000, the ISM Manufacturing PMI remained in expansion at 54.6, and the Services PMI increased to 55.4. At the same time, prices-paid readings were 71.1 in manufacturing and 72.6 in services. July headline and core PCE inflation also remained above the Federal Reserve’s 2% objective. Growth is not running away, but the data do not yet describe the clean slowdown that typically anchors long yields.
Neutral across the three Treasury ranges is therefore a choice to diversify rate exposure rather than predict one outcome. The 1–3 Year range offers liquidity and relatively modest price sensitivity. The 3–10 Year range offers a more balanced mix of income and potential appreciation. The 10+ Year range provides recession protection, but only in benchmark-sized exposure while its trend signals remain weak.
The watchlist is straightforward: the September Fed decision, August CPI, Treasury auction demand, breakeven inflation, oil, and the slope between two- and 30-year yields. Softer inflation with stable auction demand would strengthen the case for duration. A further rise in long bond yields alongside anchored short rates would suggest that term premium—not Fed policy—is still controlling the market.
Figure 1: A positively sloped curve improves Treasury income, but bearish long-duration signals keep exposure neutral.
U.S. TIPS — NEUTRAL
Short-term TIPS move to neutral as the signal set reaches an even three-to-three split. RSI, commodity-price trends, and inflation expectations are bullish. Momentum mean reversion, the moving-average cross, and the high-yield-spread relationship are bearish. The improvement is enough to remove the underweight, but not enough to make inflation protection a directional conviction.
The inflation case is more concrete than it was a month ago. July headline PCE inflation was 3.7% year over year and core PCE was 3.3%. August ISM surveys showed persistent input-cost pressure, while energy and food prices remained exposed to geopolitical and weather shocks. Market expectations also firmed: five-year breakeven inflation was approximately 2.37% and the 10-year rate about 2.35% on September 3.
Real yields remain the counterweight. The five-year TIPS real yield was near 2.2% and the 10-year real yield near 2.4% in early September. Those levels improve prospective income, but rising real yields can still pressure existing TIPS prices. Shorter maturities reduce that sensitivity and make the inflation adjustment the more important part of the position.
Neutral exposure recognizes both sides of the trade. TIPS may help if inflation remains sticky or commodity pressure broadens, but they are not immune to a renewed rise in real rates. We would look for a positive trend crossover, more stable real yields, or a better entry in breakevens before increasing the allocation
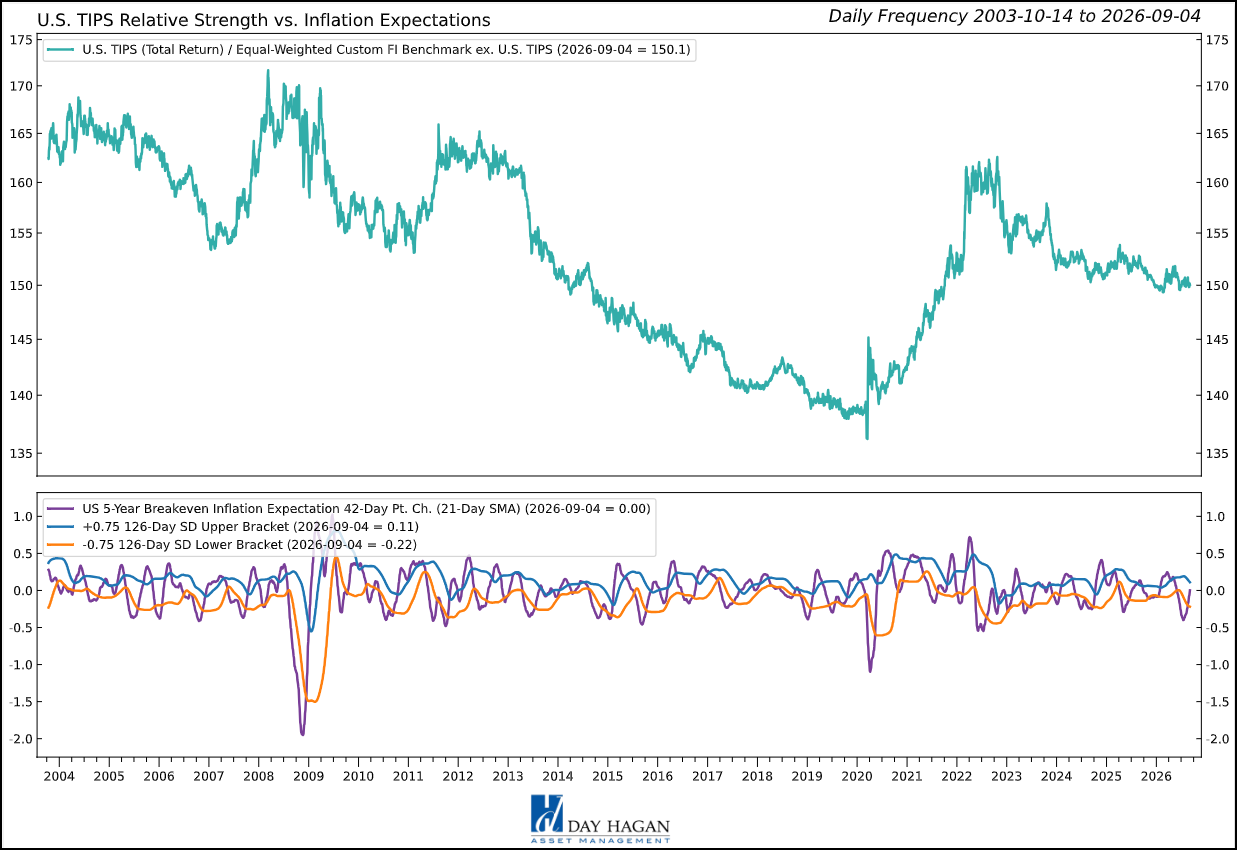
Figure 2: Firmer inflation signals justify neutral short-term TIPS exposure, while trend and real-yield risk limit conviction.
U.S. MORTGAGE-BACKED SECURITIES — UNDERWEIGHT
Agency MBS move to underweight because technical deterioration now outweighs their high-quality income. Only RSI and the 10-year-yield relationship are bullish. The moving-average cross, relative-strength slope, high-yield OAS relationship, and inflation-expectations signal are bearish. The credit guarantee has not changed; the market’s compensation for prepayment and extension risk has become less convincing.
Mortgage rates remain high enough to keep many borrowers locked into older loans. Freddie Mac’s average 30-year mortgage rate was 6.71% on September 3, up from 6.66% a week earlier. Slow refinancing can make cash flows more predictable, but it also causes mortgage duration to extend when Treasury yields rise—the wrong convexity at the wrong point in a long-end selloff.
The relative-value argument is also less generous. Investment-grade corporate spreads were near 81 basis points in early September, and agency MBS must compete with Treasuries, corporates, and a growing global supply of fixed income. Banks, insurers, money managers, and overseas buyers remain important, but the Federal Reserve is no longer providing the incremental demand it once did.
An underweight does not imply concern about agency credit. It reflects unfavorable trend confirmation and the possibility that another move higher in the 10-year yield lengthens duration just as prices decline. The sector could become attractive again if rate volatility settles, the relative-strength slope turns higher, or spreads widen enough to compensate for convexity.
For September, watch the 10-year Treasury, mortgage rates, prepayment speeds, bank demand, and Federal Reserve balance-sheet policy. A stable-rate environment with persistently high mortgage coupons would improve the carry case. A disorderly rise in long yields would probably create a better entry later, but it argues for patience now.
Figure 3: Weak trend confirmation and extension risk move agency MBS to underweight despite government-backed credit quality.
U.S. FLOATING RATE NOTES — NEUTRAL
Floating-rate notes remain neutral even though all five indicators are bullish. The technical cross, momentum, relative-strength slope, OIS relationship, and VIX-extremes signal each support the sector. That is the cleanest model confirmation in the portfolio, and it explains why floating-rate exposure remains an important source of income and low duration.
SOFR was 3.66% on September 3, close to the Federal Reserve’s 3.50%–3.75% target range. Floating coupons therefore reset at levels that remain competitive with cash without absorbing the price sensitivity of the long end. The stronger August jobs report and firm ISM price readings also reduced the urgency for policy easing, which supports near-term coupon income.
The neutral rating reflects payoff asymmetry, not a weak signal set. Floating-rate notes generally offer limited price appreciation if the Fed eventually cuts, and credit-sensitive structures can carry more risk than their low duration suggests. Short Treasuries offer simpler liquidity, while selected fixed-rate bonds would benefit more from a meaningful decline in yields.
We are comfortable being paid while the policy path develops. A renewed hiking cycle would support coupons; a decisive slowdown would make fixed-rate duration more attractive. Neutral exposure preserves both the current income and the ability to rotate when the evidence becomes less balanced.
Figure 4: Five bullish indicators support floating-rate income, while limited upside in a falling-rate scenario keeps the position neutral.
U.S. IG CORPORATE BONDS — UNDERWEIGHT
U.S. IG Corporate Bonds remain underweight. The broad composite model has one bullish input—credit-default swaps—and five bearish inputs: implied bond volatility, option-adjusted spreads, the U.S. dollar, the technical cross, and price mean reversion. This is the weakest signal balance in the portfolio. Credit fundamentals are not broadly distressed, but trend, duration, valuation, and supply leave little room for disappointment.
Spreads remain the central valuation issue. The investment-grade corporate OAS was approximately 81 basis points on September 3. All-in yields are attractive because Treasury yields are high, but the incremental premium for corporate risk is modest. In a broad aggregate allocation, investors also inherit meaningful duration at a time when long government yields remain unstable.
Supply adds another layer. U.S. corporate issuance reached roughly $1.68 trillion by mid-August, according to market estimates, and AI-related borrowers have become unusually large users of the bond market. Global corporate issuance was reported near a record $4.9 trillion through August. Strong issuers can service debt and still pressure secondary prices if new supply repeatedly arrives with concessions.
Recent company results have generally supported credit quality, but the financing question is moving from whether large technology companies can borrow to how much capital the market must absorb. Data centers, power generation, and network investment are long-lived assets. Their funding schedules may compete with Treasury issuance and other corporate borrowers for the same buyers.
The underweight favors shorter, higher-quality issues over broad index exposure and long corporates. We are watching new-issue concessions, fund flows, downgrade activity, interest coverage, and AI-related capital spending. A supply-driven widening with stable fundamentals could create opportunity. Wider spreads accompanied by weaker earnings or rising leverage would require more patience.
Figure 5: Tight spreads, heavy issuance, and bearish trend signals outweigh attractive all-in yields in U.S. corporate aggregate bonds.
U.S. HIGH YIELD — OVERWEIGHT
U.S. High Yield remains overweight. The indicator set is evenly split. The technical cross, absolute total-return moving-average cross, and VIX moving-average relationship are bullish. High-yield breadth, the small-cap equity trend, and OAS reversals are bearish. The trend has not failed, but participation and spread behavior argue against treating the sector as uniformly attractive.
The broad high-yield OAS was about 265 basis points on September 3; single-B spreads were approximately 276 basis points. Those are not recession-level cushions. The case for the overweight rests on income, continued access to refinancing, and the absence of a broad default cycle—not on unusually cheap valuations. A modest widening can be absorbed by carry; a sustained growth shock cannot.
The August employment report and expanding business surveys support issuer revenue and refinancing access. Equity volatility was also subdued entering September. The bearish breadth and small-cap readings are still important because lower-quality borrowers often feel slower growth, wage pressure, and tighter lending standards before the large-cap economy does.
New credit tied to AI infrastructure deserves special scrutiny. The projects can be economically productive and still carry construction, power-price, customer-concentration, and terminal-value risk. High coupons should not be confused with adequate compensation. We prefer businesses with visible free cash flow and multiple sources of repayment over structures that require uninterrupted capital-market access.
The overweight emphasizes BB and stronger single-B issuers, secured claims, manageable maturities, and liquidity. We are watching breadth, CCC spreads, distressed exchanges, private-credit payment-in-kind income, small-cap equities, and defaults. If trend and breadth weaken together, the position should be reconsidered; if spreads widen without fundamental deterioration, prospective income would improve.
Figure 6: High-yield trend and income remain supportive, but weak breadth and tight spreads require selective exposure.
INTERNATIONAL IG CORPORATE BONDS — NEUTRAL
International IG Corporate Bonds move to neutral as the composite model improved to three bullish readings and two bearish readings. Relative-strength slope, the moving-average cross, and credit-default swaps are bullish. Equity risk/VIX and option-adjusted spreads are bearish. The signal mix now supports benchmark exposure, but not an overweight while global yields and currencies remain unusually sensitive to policy surprises.
August’s bond selloff was global. In early September, Japan’s 10-year yield reached 3% for the first time since 1996, while U.K. gilt and euro-area government yields traded near multi-year highs. The European Central Bank held its deposit rate at 2.25% in July, the Bank of England held Bank Rate at 3.75% with three members favoring an increase, and the Bank of Japan maintained a 1.0% policy rate. Each market is confronting its own mix of inflation, fiscal supply, and currency pressure.
Currency remains part of the return for unhedged investors. The dollar weakened into September 3, then strengthened after the U.S. jobs report. The yen has been especially volatile as markets weigh additional Bank of Japan tightening and the possibility of continued intervention. A stronger euro or pound can help dollar-based returns, but that benefit can disappear quickly when relative policy expectations change.
Neutral exposure recognizes the diversification value of non-U.S. duration without assuming that foreign central banks will ease before the Fed. The improving technical and CDS signals are constructive. Tight spreads and rising global term premiums argue for measured sizing and careful attention to hedging costs.
We are watching the September meetings of the ECB, Fed, and Bank of Japan, European energy inflation, U.K. fiscal policy, Japanese wage data, and currency volatility. Falling local yields with a stable or firmer foreign currency would improve the opportunity. Rising yields paired with a weaker currency would be the most difficult combination for an unhedged U.S. investor.
Figure 7: Better trend and CDS confirmation move international bonds to neutral, while policy and currency volatility limit conviction.
EMERGING MARKET BONDS — OVERWEIGHT
Emerging-Market Bonds remain overweight with four bullish readings and one bearish reading. The EM currency index versus the dollar, emerging-equity momentum, commodity strength, and relative-strength slope are bullish. The absolute moving-average cross is bearish. This is broad confirmation, although it does not remove sensitivity to U.S. real yields or country-specific policy mistakes.
The currency signal deserves emphasis even for USD-denominated debt. A stable or weaker dollar generally eases external financing conditions and supports local reserves. The dollar’s rebound after the August jobs report is a reminder that this tailwind can reverse when U.S. rate expectations change. Hard-currency bonds avoid direct local-currency exposure, but sovereign spreads still respond to the same global liquidity cycle.
Commodities remain a differentiator. Firm energy prices can support exporters while pressuring importers’ inflation and current accounts. Metals and agricultural prices create different winners and losers, so the model’s bullish commodity input is not a reason to own every issuer. Country selection, reserve adequacy, and fiscal credibility remain essential.
Valuation is supportive relative to developed-market investment grade, but not uniformly cheap. The overweight therefore favors liquid sovereign and quasi-sovereign issuers, diversified regional exposure, and countries with credible central banks and manageable external refinancing calendars. Lower-quality credits that depend on uninterrupted access to dollars require more spread than the market currently offers.
The September watchlist includes U.S. real yields, the dollar, China’s growth data, commodity prices, reserve trends, elections, and sovereign issuance. A stable dollar with firm commodities and improving EM equities would support the position. A renewed dollar surge, weaker commodity demand, or a break in the relative-strength trend would challenge it.
Figure 8: Currency, equity, commodity, and relative-strength signals support the emerging-market bond overweight.
Catastrophic Stop Model
The Catastrophic Stop model combines time-tested, objective indicators to identify high-risk periods for equities and fixed-income assets that are highly correlated with the equity market. The model entered September recommending a fully invested allocation relative to the benchmark for equity-sensitive credit sectors.
The current reading indicates that recent equity weakness is not yet consistent with a significant downtrend. If the model falls below 40% for two consecutive days, it would trigger a sell signal and the strategy would reduce exposure. The model can respond to changing conditions, but no signal can eliminate loss or identify every market turning point.
Figure 9: The Catastrophic Stop model recommends a fully invested position relative to the benchmark. Because the model uses indices to extend its history, the historical illustration is considered hypothetical.
Hypothetical and historical past performance is not indicative of future results. There can be no assurance that any investment or strategy will achieve its objectives or avoid substantial losses or have comparable results. This information is provided for illustrative purposes only and is not a prediction, projection, or guarantee of future performance. Hypothetical results do not reflect actual trading, were derived using the benefit of hindsight, and may not reflect material economic and market events. Actual results vary and depend on many factors and subject to risk and uncertainties.
Our goal is to participate while the prevailing trend is constructive and to reduce equity-sensitive credit exposure when conditions deteriorate. The Catastrophic Stop model is currently positive, while the sector composites remain differentiated: strongest in floating-rate and emerging-market bonds, balanced in high yield and global bonds, and weakest in the broad U.S. Aggregate and long Treasuries. The portfolio is aligned with that message.
This strategy uses price, valuation, economic, liquidity, and sentiment measures to make objective allocation decisions. Model signals are inputs, not guarantees. They may change without notice, and there is no assurance that an overweight will outperform, an underweight will reduce loss, or the Catastrophic Stop model will avoid a market decline.
For more information, please contact us at:
Day Hagan Asset Management
1000 S. Tamiami Trl
Sarasota, FL 34236
Toll Free: (800) 594-7930
Office Phone: (941) 330-1702
Website: https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved.
Day Hagan Smart Sector® Fixed Income ETF
Symbol: SSFI
Disclosures
The data and analysis contained within are provided “as is” and without warranty of any kind, either express or implied. The information is based on data believed to be reliable, but it is not guaranteed. Day Hagan DISCLAIMS ANY AND ALL EXPRESS OR IMPLIED WARRANTIES, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY, SUITABILITY, OR FITNESS FOR A PARTICULAR PURPOSE OR USE. All performance measures do not reflect tax consequences, execution, commissions, and other trading costs, and as such, investors should consult their tax advisors before making investment decisions, as well as realize that the past performance and results of the model are not a guarantee of future results. The Smart Sector® Strategy is not intended to be the primary basis for investment decisions, and the usage of the model does not address the suitability of any particular investment for any particular investor.
Using any graph, chart, formula, model, or other device to assist in deciding which securities to trade or when to trade them presents many difficulties, and their effectiveness has significant limitations, including that prior patterns may not repeat themselves continuously or on any particular occasion. In addition, market participants using such devices can impact the market in a way that changes the effectiveness of such devices. Day Hagan believes no individual graph, chart, formula, model, or other device should be used as the sole basis for any investment decision and suggests that all market participants consider differing viewpoints and use a weight-of-the-evidence approach that fits their investment needs.
Past performance does not guarantee future results. No current or prospective client should assume future performance of any specific investment or strategy will be profitable or equal to past performance levels. All investment strategies have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals, and economic conditions may materially alter the performance of your portfolio. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. Historical performance results for investment indexes and/or categories generally do not reflect the deduction of transaction and/or custodial charges or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing historical performance results. There can be no assurances that a portfolio will match or outperform any particular benchmark. Comparisons to indices are inherently unreliable indicators of future performance. The strategies used to generate the performance vary from those used to generate the returns depicted in the benchmarks. Investors cannot directly invest in an index.
The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
The material may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved.
All hypothetical results are presented for illustrative purposes only. Back testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
© 2026 Day Hagan Asset Management
Disclosure
Federal Reserve (Fed) — The central bank of the United States, responsible for setting monetary policy and short-term interest rates.
U.S. Treasuries — Bonds issued by the U.S. government; they are widely used as benchmarks for interest rates and as defensive assets in portfolios.
T-bill (Treasury bill) — A short-term U.S. government security, typically maturing in one year or less.
Duration — A measure of a bond’s sensitivity to changes in interest rates; higher duration usually means greater price movement when yields change.
Yield — The income return on a bond, usually expressed as an annual percentage of its price.
Investment-Grade (IG) Corporate Bonds — Corporate bonds with relatively high credit quality and lower default risk than high-yield bonds.
High-Yield (HY) Bonds — Lower-rated corporate bonds that offer higher yields because they carry higher credit risk.
Private Credit — Non-bank lending, often directly to companies, outside the public bond markets.
TIPS (Treasury Inflation-Protected Securities) — U.S. government bonds designed to protect investors from inflation by adjusting principal based on inflation.
Breakeven Inflation Rate — The market’s implied inflation expectation, calculated as the difference between nominal Treasury yields and TIPS yields.
Real Yield — A bond yield after adjusting for inflation; often referenced in connection with TIPS.
Nominal Yield — A bond yield not adjusted for inflation.
Inflation Expectations — The market’s view of future inflation, which influences both bond yields and asset prices.
Mortgage-Backed Securities (MBS) — Bonds backed by pools of home mortgages; investors receive cash flows from underlying mortgage payments.
Agency MBS — Mortgage-backed securities issued or guaranteed by U.S. government-related agencies, generally viewed as having high credit quality.
Floating Rate Notes (FRNs) — Bonds whose interest payments reset periodically based on a short-term reference rate, reducing interest-rate sensitivity.
SOFR (Secured Overnight Financing Rate) — A key U.S. benchmark short-term interest rate used in loans, derivatives, and floating-rate instruments.
OIS (Overnight Index Swap) Rate — A rate derived from swaps tied to overnight interest rates, often used to gauge policy-rate expectations.
Primary Issuance — The sale of new bonds into the market by governments or companies.
Spread — The yield difference between one bond and a benchmark, often used to measure compensation for credit risk.
Option-Adjusted Spread (OAS) — A spread measure that adjusts for embedded bond options, commonly used in corporate bonds and mortgage-backed securities.
Credit Default Swap (CDS) — A derivative contract used to insure against bond default risk; rising CDS levels often signal greater credit concern.
Carry — The return earned from holding a bond or credit asset, assuming market conditions remain stable.
Refinancing Risk — The risk that a borrower will face higher costs or difficulty when replacing maturing debt with new debt.
Emerging Market (EM) Bonds — Debt issued by governments or companies in developing economies.
Hard-Currency Debt — Emerging-market debt issued in a major foreign currency, usually U.S. dollars or euros.
Local-Currency Debt — Emerging-market debt issued in the borrower’s domestic currency, making returns more sensitive to exchange-rate movements.
Risk-On / Risk-Off — Market environments where investors are either more willing to buy riskier assets (“risk-on”) or prefer safer assets (“risk-off”).
RSI (Relative Strength Index) — A technical indicator used to assess whether an asset may be overbought or oversold.
VIX — A widely followed measure of U.S. equity market volatility, often called the market’s “fear gauge.”