A downloadable PDF copy of the Article:
Day Hagan Smart Sector® International Strategy Update November 2026 (pdf)
Executive Summary
We enter November overweight Germany, Japan, Switzerland, and the United Kingdom. Canada, the Netherlands, and Taiwan are neutral. Australia, China, France, India, and South Korea are underweight. Germany and the United Kingdom move higher in the allocation, Canada moves to neutral, and we reduce South Korea and Taiwan. These changes reflect a widening separation between economic opportunity and the price investors are willing to pay for it.
The international backdrop has become more demanding. Higher energy costs are putting renewed pressure on inflation, household purchasing power, and corporate margins. At the same time, investment in artificial intelligence continues to support selected technology businesses. The resulting opportunities differ considerably across countries and industries. A strong technology order book can coexist with weak consumer demand, and a growing economy can still have an underperforming stock market.
Our Core sleeve represents approximately 85% of equity holdings. The Explore sleeve accounts for approximately 15% and now includes Brazil, Chile, Peru, Singapore, and Israel. The portfolio combines exposure to established global businesses with smaller tactical country positions. We continue to adjust allocations as the balance of evidence changes.
Economic and Policy Outlook
Inflation is again influencing the range of choices available to central banks. The ECB held its deposit rate at 2.50% on October 29, while warning that a prolonged energy shock could raise inflation and weaken growth. The Bank of Canada increased its policy rate to 2.50% on October 28. Australia and the United Kingdom also reported higher annual inflation for September. Investors should be cautious about assuming that softer activity will automatically produce easier monetary policy.
For companies and sectors, the important questions are more direct. Can selling prices keep pace with wages, fuel, freight, and financing costs? Does a large order book convert into revenue and cash, or require further spending before profits arrive? Banks may earn more on loans when interest rates rise, but deposit costs and borrower stress can offset that benefit. Commodity producers can gain from stronger selling prices while manufacturers and consumers absorb higher input costs.
AI investment remains an important source of demand across the international technology supply chain. ASML, Samsung, TSMC, and SAP reported developments that illustrate its reach across semiconductor equipment, memory, chip production, and enterprise software. However, those businesses face different capacity, customer, and cash-flow risks. We are maintaining exposure selectively rather than treating every technology-oriented country as the same investment.
Currency adds another layer. A stronger local currency can help the dollar value of an unhedged investment while reducing the translated overseas earnings of a domestic exporter. A weaker currency may support an exporter’s competitiveness but increase imported energy costs. Our country positioning considers these competing effects alongside valuation and market evidence.
Holdings
Core: Developed Market Positions (approximately 85% of equity holdings)
Country
Australia
Canada
China
France
Germany
India
Japan
Netherlands
South Korea
Switzerland
Taiwan
United Kingdom
Outlook
Underweight
Neutral
Underweight
Underweight
Overweight
Underweight
Overweight
Neutral
Underweight
Overweight
Neutral
Overweight
Explore: Emerging Market Positions (approximately 15% of equity holdings)
Brazil
Chile
Peru
Singapore
Israel
Position Details
Core Developed Market Commentary
Approximately 85% of the strategy is allocated across 12 large, liquid non-U.S. equity markets. The fund overweights and underweights these markets based on macro, fundamental, behavioral, currency, and technical indicators.
AUSTRALIA — UNDERWEIGHT
Australia remains underweight. Renewed inflation pressure complicates the outlook for household spending and interest-sensitive businesses. September consumer prices rose 4.3% from a year earlier, up from 4.0% in August. Trimmed mean inflation, which reduces the influence of unusually large price changes, increased to 3.6%. The breadth of that pressure matters because it can delay relief in financing costs even if parts of the economy soften.
At the company level, the effects vary. Banks must balance loan income against deposit competition, mortgage affordability, and potential credit losses. Retailers face the risk that higher essential expenses leave households with less room for discretionary purchases. Resource businesses depend on the prices they receive, production costs, and the demand behind those prices. A favorable gold market does not automatically resolve the outlook for industrial commodities or the wider equity market.
China remains an important part of the demand picture. Its uneven consumer environment argues for distinguishing strong export or technology activity from a broad recovery in domestic demand. Our underweight recognizes these competing pressures. The model evidence remains predominantly unfavorable, including relative earnings yield, and does not yet justify increasing exposure.
Figure 1: Relative earnings yield remains unfavorable.
CANADA — NEUTRAL
Canada moves to neutral as improved market trends meet a firmer, but more complicated, economic backdrop. On October 28, the Bank of Canada raised its policy rate by 25 basis points to 2.50%. Its assessment described stronger business investment, including oil and gas activity and machinery spending, while noting continuing weakness in industries affected by U.S. tariffs. It also warned that elevated energy costs could spread more broadly into prices.
The corporate implications are uneven. Higher energy revenue can support producers’ cash generation and investment, while higher fuel and transport bills raise costs for other companies. Businesses selling into the United States remain exposed to trade rules as well as American demand. Banks must weigh the benefit of higher lending yields against deposit costs, mortgage renewals, and the quality of commercial loan books.
For a dollar-based investor, Canadian-dollar movements can amplify or offset local equity results. Currency support is not assured simply because the central bank has raised rates. The move to neutral acknowledges better price confirmation while retaining caution about earnings valuation, trade exposure, and the consumer. We would look for broader improvement before increasing Canada above its benchmark allocation.
Figure 2: An improving absolute trend supports the move to neutral.
CHINA — UNDERWEIGHT
China remains underweight as the gap between selected areas of industrial strength and broader household demand remains important. September retail sales increased 1.1% from a year earlier in nominal terms. Sales excluding automobiles rose 3.9%, while automobile sales were substantially weaker. These figures point to an uneven spending environment and caution against reading strength in one industry as evidence of a broad consumer recovery.
For consumer companies, the issues are sales volumes, promotional spending, and the ability to protect margins. For industrial and technology exporters, overseas demand can help offset domestic weakness, but trade restrictions and customer concentration remain risks. Property-related balance sheets also matter through their links to household confidence, collateral values, and local business cash flow. These channels can take time to improve even when policy support increases.
The allocation remains cautious because the favorable manufacturing-survey relationship has not been accompanied by broad price, currency, or credit confirmation. The credit chart below reinforces that caution, but should be read as a global risk-appetite input. We would need a more consistent improvement in demand, earnings quality, and market leadership to support a larger allocation.
Figure 3: The credit-risk relationship remains a warning.
FRANCE — UNDERWEIGHT
France remains underweight. The first estimate of third-quarter GDP showed a 0.1% decline from the prior quarter. Household consumption increased, but investment fell 0.6% and exports declined 1.7%. That combination places more weight on companies’ ability to generate growth from their own products and markets while domestic investment remains weak.
Luxury demand provides a useful company-level example. LVMH reported third-quarter organic revenue growth of 1%, but Fashion and Leather Goods revenue declined 5% on the same basis. The company described a less buoyant environment in China, alongside growth in the United States, Europe, and Japan. Demand is therefore varying by geography and product category, with implications for inventories, pricing, and operating margins.
Higher energy and financing costs add pressure to this backdrop. Exporters must also manage the effect of currency movements on overseas sales and reported earnings. Banks and other domestic businesses remain sensitive to household confidence and the cost of capital. Attractive valuation and dividend measures provide some support, but weak market participation still argues for patience. We retain the underweight while watching for a broader recovery in investment, exports, and earnings delivery.
Figure 4: Weak relative breadth supports continued caution.
GERMANY — OVERWEIGHT
Germany moves to overweight even though the domestic recovery remains modest. Third-quarter GDP rose 0.2% from the previous quarter after adjustment for prices, seasonality, and calendar effects. Consumption improved slightly, while capital formation weakened and export momentum slowed. The distinction between the domestic economy and internationally active listed companies remains important.
SAP illustrates one area of stronger corporate demand. Third-quarter cloud revenue increased 25% at constant currencies, and its current cloud backlog grew 26% on that basis. Those figures point to continued spending on enterprise technology even when traditional industrial demand is less consistent. The investment question is whether that demand converts into profitable revenue and cash flow as implementation and development spending continue.
Other businesses face a different balance of risks. Energy-intensive manufacturers must manage input costs, while exporters depend on global orders, trade conditions, and currency translation. Higher financing costs can delay customers’ capital spending. Our increased allocation is supported by improved market participation and relative trends, alongside favorable valuation and flow inputs. It does not require assuming that every part of German manufacturing has recovered. We will watch order conversion, margins, and the breadth of earnings improvement.
Figure 5: Improving relative trend supports the higher allocation.
INDIA — UNDERWEIGHT
India remains underweight. September CPI inflation rose to a provisional 5.54% from 4.83% in August, with food inflation at 7.74%. Higher food costs can reduce discretionary purchasing power, particularly for households with limited room in their budgets. Imported energy costs and currency movements can add to pressure on business margins and the external accounts.
Company results show that opportunities remain selective. TCS reported revenue growth of 2.4% in U.S. dollars from a year earlier for the quarter ended September 30. Its international revenue increased sequentially in constant currency, and it reported continued growth in AI-related activity. These developments support the longer-term technology services opportunity, but project demand, pricing, and the cost of adapting delivery models remain important. A promising product category does not automatically produce rapid growth across an entire company or market.
For domestic lenders and consumer businesses, deposit costs, credit quality, household income, and the ability to pass through inflation deserve close attention. Our underweight reflects weak confirmation across most of the supplied country evidence, including earnings and currency relationships. We continue to distinguish India’s long-term economic potential from the valuation and earnings support available to investors today.
Figure 6: The forward-earnings relationship remains unfavorable.
NETHERLANDS — NEUTRAL
The Netherlands remains neutral. Semiconductor equipment provides an important window into the corporate backdrop. ASML reported third-quarter sales of €11.7 billion and a gross margin of 57.5%. Its commentary described strong AI-related demand and the need to expand capacity to meet customers’ longer-term requirements. This supports the investment case for equipment spending while highlighting the practical challenge of delivering complex systems on schedule.
A strong order environment does not remove execution risk. Supplier capacity, customer fab readiness, installation timing, and working-capital needs all affect when orders become revenue and cash. Export restrictions can influence the mix of customers and products. Large technology capital budgets also require funding, and higher financing costs can change the timing of projects even when their strategic rationale remains intact.
Outside technology, the euro-area energy and interest-rate backdrop continues to affect margins and demand. Currency movements can help the dollar value of an unhedged position while creating a different effect on exporters’ earnings. Neutral exposure retains participation in the semiconductor investment cycle while acknowledging the model’s weaker forward-earnings and currency relationships. We would prefer broader earnings confirmation before increasing the country allocation.
Figure 7: The semiconductor relationship remains supportive.
SOUTH KOREA — UNDERWEIGHT
South Korea moves from overweight to underweight. AI-related demand remains a meaningful corporate opportunity, but the country’s earnings picture is less uniform than that theme alone suggests. Samsung’s third-quarter release reported record memory revenue and profit, supported by demand for advanced products, while its Device eXperience division recorded an operating loss. The contrast shows why stronger memory economics should not be applied automatically to consumer devices or the broader market.
For semiconductor producers, product mix, manufacturing yields, customer qualifications, and the cost of expanding capacity determine how much demand translates into profit. Capacity constraints can support pricing while also limiting shipments. In other industries, energy costs, global consumer spending, and trade conditions can affect margins and order volumes. Currency weakness can help export competitiveness but raise imported costs and reduce dollar-translated investment returns.
Our reduced allocation reflects a deterioration in the supplied country evidence, including trend and forward-earnings measures. Favorable elements remain, but they do not yet outweigh the broader warnings. We will watch whether technology strength spreads into more consistent earnings growth and whether market leadership improves beyond a narrow group of beneficiaries.
Figure 8: Trend signals turning negative.
TAIWAN — NEUTRAL
Taiwan moves to neutral despite continued strength in advanced semiconductor demand. TSMC reported third-quarter U.S.-dollar revenue growth of 41.2% from a year earlier and a gross margin of 66.4%. Advanced technologies of seven nanometers and below represented 79% of wafer revenue. Those results demonstrate the importance of leading-edge manufacturing to the current technology investment cycle.
For investors, the next questions concern the return on the spending required to meet that demand. New process nodes and overseas facilities require capital, skilled labor, utilities, and reliable supply chains. Customer concentration, export rules, and geopolitical risk can affect both operations and the valuation investors assign to future earnings. Strong demand can therefore coexist with a higher burden of execution.
Taiwan also remains sensitive to imported energy costs and exchange rates. A stronger local currency can help dollar-translated equity returns while changing the value of overseas sales for exporters. The move to neutral acknowledges the attractive corporate opportunity while reducing reliance on it. The trend and semiconductor-related signals have weakened, leaving a more balanced case than in October. We would look for renewed market confirmation alongside continued earnings delivery before restoring an overweight.
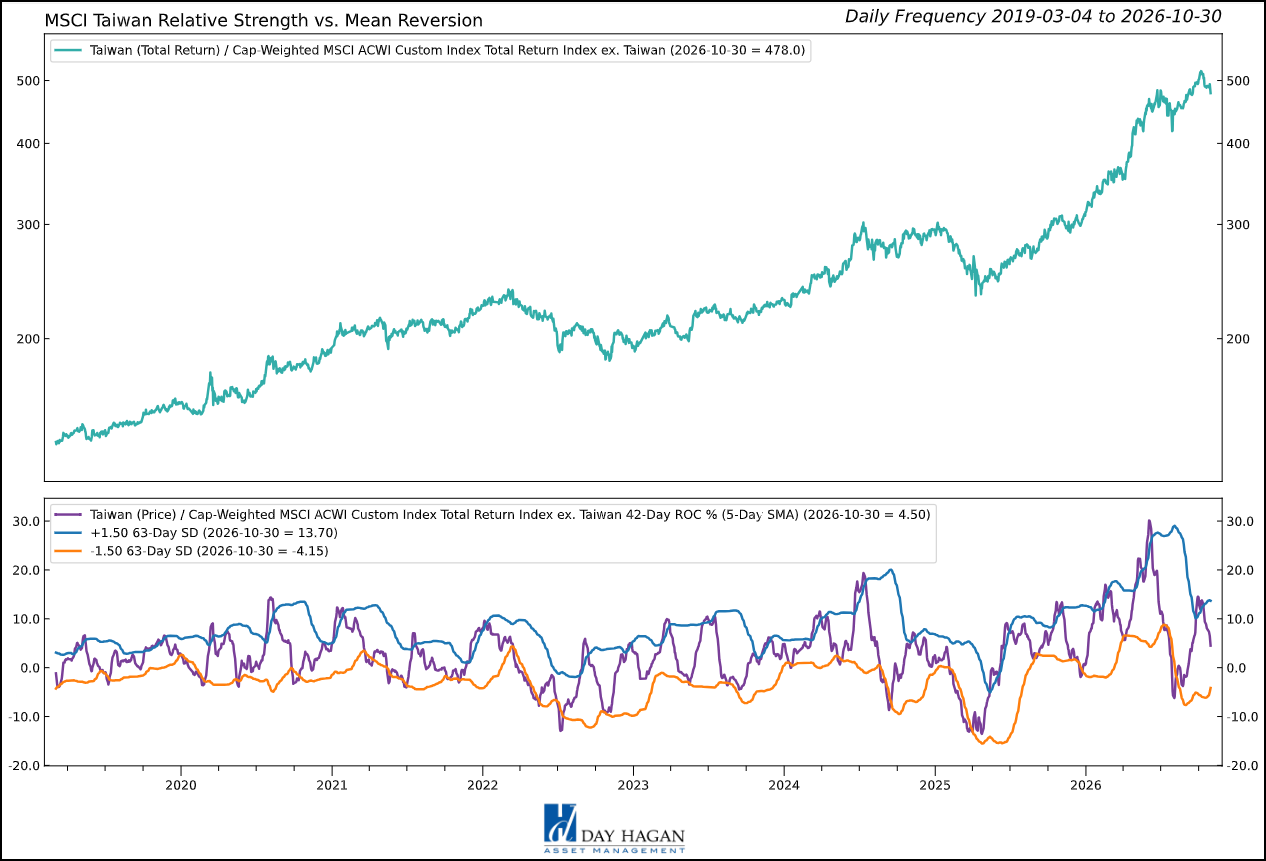
Figure 9: The trend warning supports a more balanced allocation.
JAPAN — OVERWEIGHT
Japan remains overweight as favorable market trends coexist with a changing policy environment. On October 30, the Bank of Japan maintained its overnight-rate guideline at around 1.25%. It also announced a faster pace of ETF sales beginning in January 2027. This is a further step in reducing the central bank’s equity holdings, although the announced sales remain small relative to overall market trading.
The effects of higher interest rates differ across businesses. Banks can benefit as asset yields adjust, but funding costs and credit quality still determine how much reaches profits. Companies with significant borrowing face higher financing expenses. Exporters must manage the yen’s effect on competitiveness and translated earnings, while households and energy-dependent businesses are sensitive to the cost of imports.
Corporate capital spending can support suppliers of machinery, automation, and technology, but orders need to convert into earnings and free cash flow. We therefore continue to watch company guidance and the balance between investment and shareholder distributions. Japan’s trend and valuation evidence supports the overweight, while the weaker earnings and currency relationships temper conviction. The allocation allows participation without assuming that monetary normalization or exchange-rate changes will benefit every industry equally.
Figure 10: Japan’s stronger trends and favorable valuation support an overweight, while earnings, sentiment, and currency signals remain cautionary.
SWITZERLAND — OVERWEIGHT
Switzerland remains overweight, providing exposure to a different set of global earnings drivers. Healthcare offers one current example. Roche reported third-quarter sales growth of 7% at constant exchange rates and confirmed its full-year outlook. Its nine-month growth was 6% at constant currencies but 1% in Swiss francs, illustrating how currency translation can materially change reported results.
The company-level questions extend beyond headline sales. For healthcare businesses, product adoption, competition, reimbursement, and research spending influence earnings durability. Consumer businesses must balance pricing with sales volumes, while financial companies depend on client activity, funding costs, and asset quality. These sources of revenue can behave differently from industrial production or semiconductor capital spending, adding useful diversification to the portfolio.
The franc creates a two-sided effect. Appreciation can increase the dollar value of an unhedged holding while making overseas earnings worth fewer francs. We therefore avoid treating currency strength as an unqualified benefit. The overweight is consistent with improving momentum and relative income evidence, although participation remains incomplete. We retain the position while watching the breadth of earnings delivery and the extent to which currency movements affect company guidance.
Figure 11: Improving relative-strength slope supports the overweight.
UNITED KINGDOM — MODEST OVERWEIGHT
The United Kingdom moves to overweight. The domestic economy faces renewed inflation pressure, with September CPI inflation rising to 3.5% from 3.1% in August. That increases the strain on household purchasing power and makes the path toward lower financing costs less straightforward. Businesses serving the domestic consumer still need to manage wages, input costs, and affordability.
Internationally active companies can have a different earnings profile. HSBC reported third-quarter profit before tax growth of 10% at constant currencies and excluding notable items. The bank also announced an intention to initiate a further share buyback of up to $1 billion. Its results illustrate how overseas operations, client activity, and capital management can influence the outlook for a London-listed business independently of the latest UK growth data. The buyback was an announced plan, not a completed distribution.
For the wider market, commodity prices, global demand, and sterling translation remain important. Banks’ income can benefit from higher rates, but deposit competition and borrower stress can offset the gain. Our increased allocation is supported by favorable relative momentum, valuation, currency, and credit relationships. We retain attention to the weaker trend and sentiment inputs as the domestic inflation backdrop becomes more difficult.
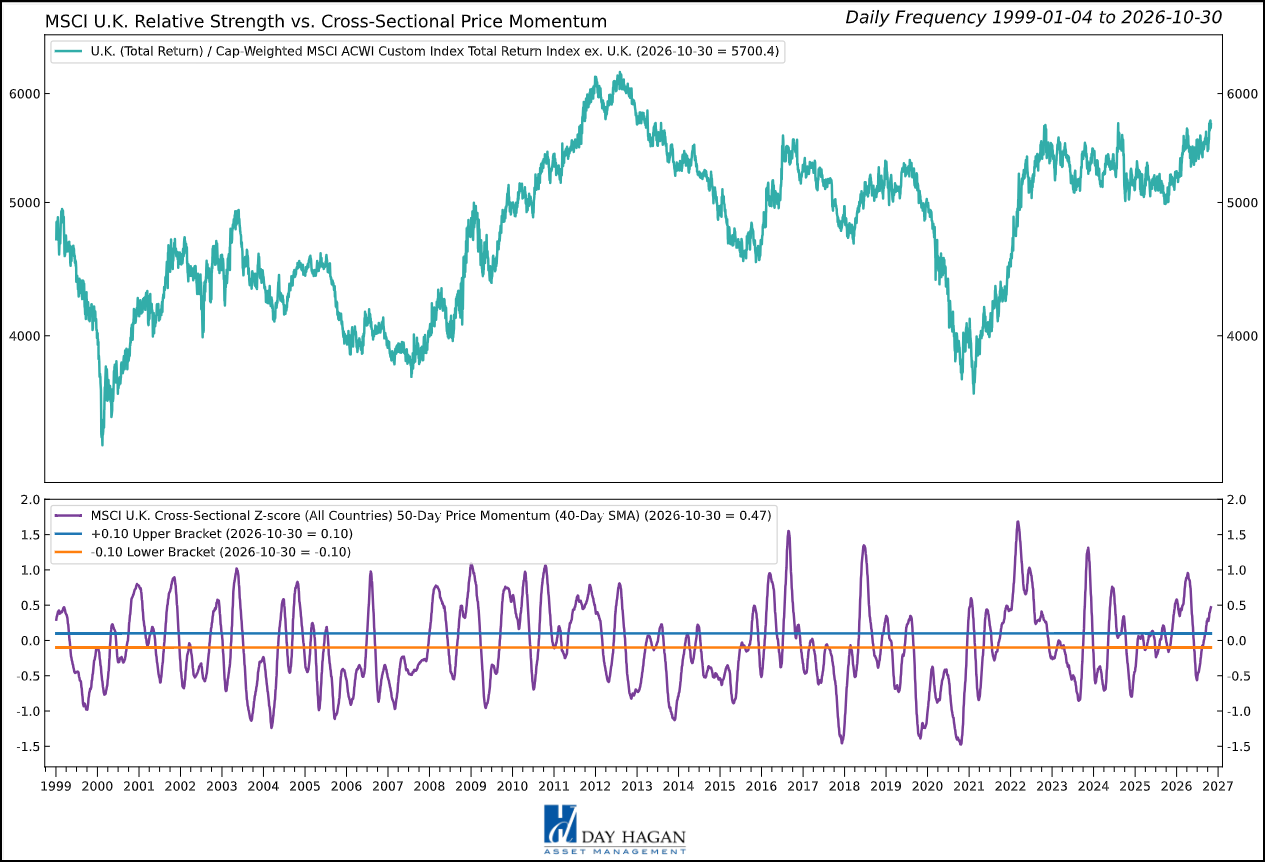
Figure 12: Improved cross-sectional momentum supports the higher allocation.
Emerging Market Positions
Approximately 15% of the strategy is allocated across five markets from a pool of more than 20 smaller markets. Selection is based on a multifactor technical ranking system that uses trend and mean-reversion indicators. The process seeks to identify oversold opportunities likely to mean-revert and modest pullbacks within longer-term uptrends. These positions can be more volatile and less liquid than the core allocation.
Current Holdings
Brazil
Chile
Peru
Singapore
Israel
Explore Emerging Market Commentary
Brazil
Brazil enters the November Explore sleeve. The September policy decision set the Selic rate at 13.75%, keeping financing costs central to the investment outlook. High rates can support local-currency carry while weighing on credit demand, investment, and equity valuations. Banks must balance lending income against borrower stress. Commodity-linked businesses have a different earnings exposure, making production costs, export receipts, and fiscal credibility important areas to monitor. The position is a tactical country allocation, not a broad endorsement of every domestic industry. Recent political upheavals and subsequent market declines are providing potential opportunity.
Chile
Chile returns to the Explore sleeve. The central bank held its policy rate at 4.50% on October 27 and warned of greater inflation risks from energy and food costs. It also described weak consumption and investment alongside a more favorable longer-term investment outlook. Copper-related activity can support export earnings, but company cash flow depends on production, grades, costs, and project execution. The peso and imported fuel costs can transmit global shocks into domestic margins.
Peru
Peru enters the Explore sleeve with the central bank’s October reference-rate series at 4.25%. Financing conditions matter for domestic lenders and consumers, while resource businesses are more sensitive to metals demand and operating execution. Copper and gold exposure can provide different drivers from the portfolio’s technology holdings, although commodity revenue does not remove political, permitting, labor, or currency risk. We will watch whether favorable export economics translate into investment and cash generation.
Singapore
Singapore joins the Explore sleeve. The Monetary Authority of Singapore maintained the prevailing appreciation path of its exchange-rate policy band on October 14. Its statement cited advance third-quarter GDP growth of 5.4% from a year earlier, supported in part by AI-related trade. Electronics and cross-border financial activity provide opportunities, while commercial property and other borrowers remain sensitive to financing costs. A trade-oriented economy also remains exposed to supply-chain disruptions and changes in global capital spending.
Israel
Israel returns to the Explore sleeve. The Bank of Israel held its policy rate at 3.25% on October 21, with September annual inflation at 1.6%. The central bank’s assessment nevertheless highlighted uncertainty, including geopolitical and currency risks. For companies, the relevant channels include staffing, financing, supply continuity, and access to overseas customers. Technology exports can provide an earnings driver distinct from domestic demand, but geopolitical developments can quickly change the risk premium investors require.
Catastrophic Stop Model
The Catastrophic Stop model combines time-tested, objective indicators designed to identify high-risk periods for the equity market. The model entered November recommending a fully invested equity allocation relative to the benchmark.
The weight of the evidence suggests that international equity exposure can remain selective and fully invested at this time. If the model triggers a sell signal below 40% for two consecutive days, indicating more substantial market stress, the strategy will raise cash in accordance with its rules. The signal is systematic and may change as market conditions evolve.
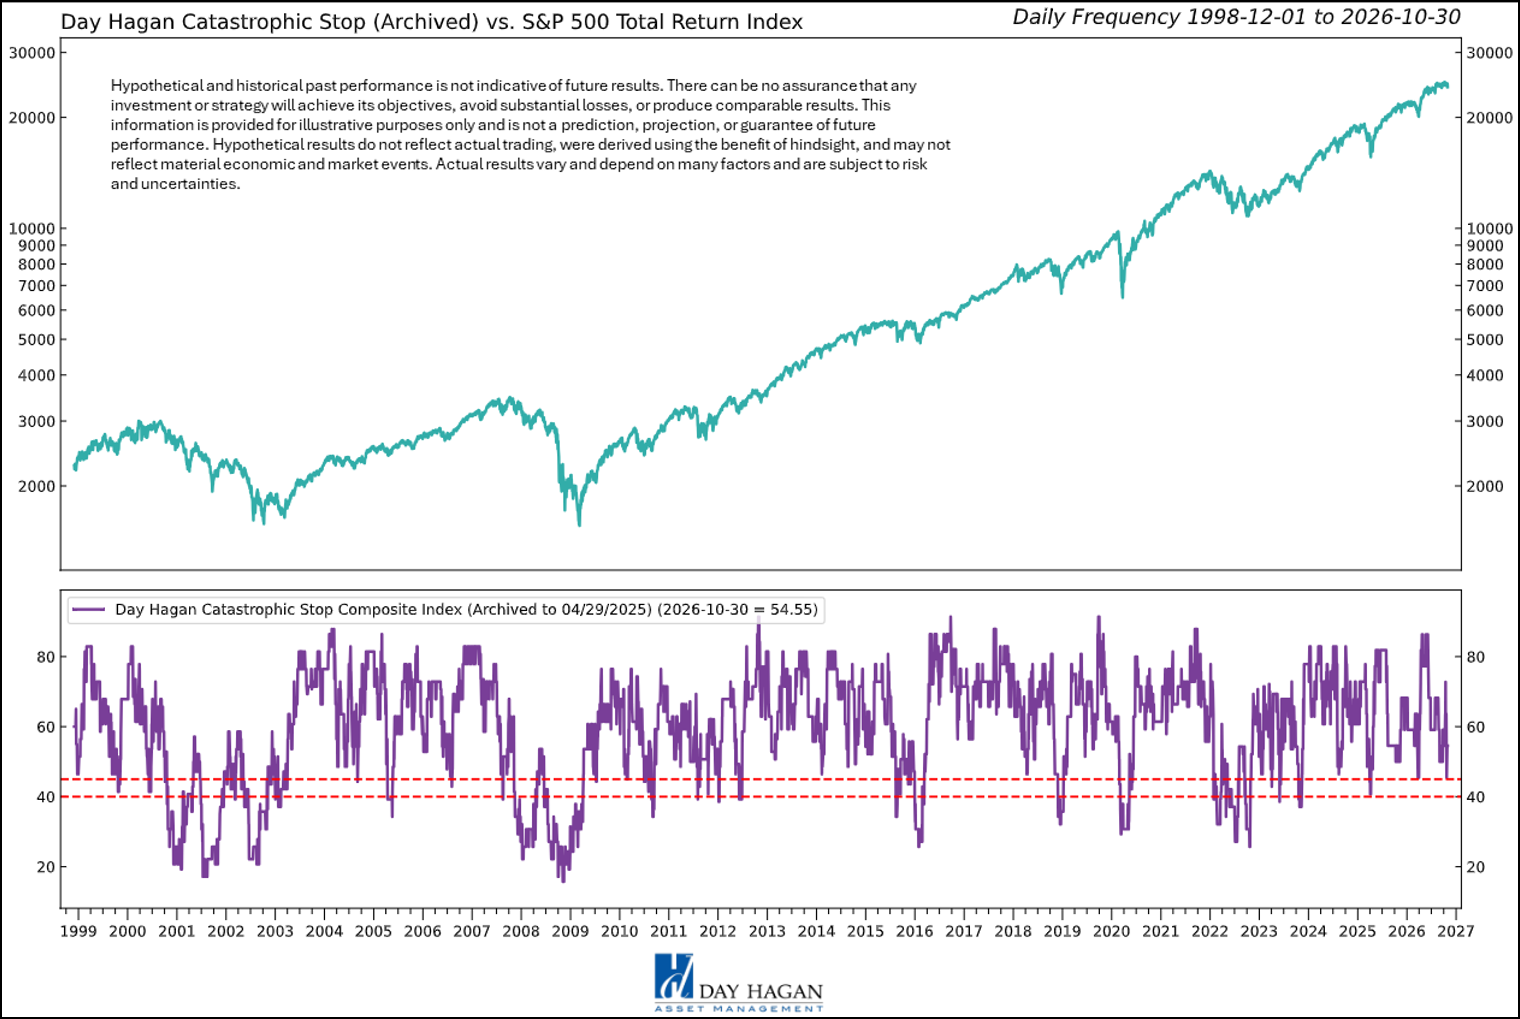
Figure 13: The Catastrophic Stop model recommends a fully invested equity position relative to the benchmark.
Conclusion
We enter November with greater relative exposure to Germany and the United Kingdom, continued overweights in Japan and Switzerland, and less exposure to South Korea and Taiwan. The changes recognize that favorable business conditions and favorable investment conditions do not always arrive together. The price paid, the quality of earnings, and the direction of market leadership remain important.
Our focus will be on whether companies can protect margins and turn spending into cash flow while energy and financing costs remain elevated. We will also watch the breadth of demand beyond AI-related activity, the effect of currencies on reported profits, and the willingness of consumers and businesses to spend. Allocations will continue to follow the evidence as those conditions change.
This strategy uses measures of price, valuation, economic trends, liquidity, and market sentiment to make objective, rational, and unemotional decisions about how much capital to risk and where to allocate it.
For more information, please contact us at:
Day Hagan Asset Management
1000 S. Tamiami Trl
Sarasota, FL 34236
Toll Free: (800) 594-7930
Office Phone: (941) 330-1702
Website: https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved. (© Copyright 2026 Day Hagan Asset Management.)
Day Hagan Smart Sector® International ETF
Symbol: SSXU
Sources
European Central Bank. Monetary policy decisions, October 29, 2026.
Australian Bureau of Statistics. Consumer Price Index, September 2026, released October 28.
Bank of Canada. Policy decision and economic assessment, October 28, 2026.
National Bureau of Statistics of China. Retail sales, September and January–September 2026, released October 20.
INSEE. Third-quarter 2026 GDP first estimate, October 30.
LVMH. Third-quarter 2026 revenue, October 12. Organic growth excludes currency and scope effects.
Destatis. Third-quarter 2026 GDP first estimate, October 30.
SAP. Third-quarter 2026 results, October 21.
India Ministry of Statistics and Programme Implementation. September 2026 CPI, October 12. September figures provisional.
Tata Consultancy Services. Second-quarter fiscal 2027 results for the quarter ended September 30, released October 8.
Bank of Japan. Statement on Monetary Policy, October 30, 2026.
ASML. Third-quarter 2026 results, October 14.
Samsung Electronics. Third-quarter 2026 results, October 29.
Roche. Third-quarter 2026 sales, October 22.
TSMC. Third-quarter 2026 earnings release, October 15.
UK Office for National Statistics. Consumer price inflation, September 2026, released October 21.
HSBC. Third-quarter 2026 quick read, results dated October 27.
Central Bank of Brazil. September 16, 2026 policy decision, effective September 17.
Central Bank of Chile. Monetary policy meeting, October 27, 2026.
Central Reserve Bank of Peru. Reference interest rate, monthly series PD04722MM, October 2026 observation.
Monetary Authority of Singapore. Monetary policy statement, October 14, 2026.
Bank of Israel. Interest-rate decision, October 21, 2026.
Disclosures
The data and analysis contained within are provided “as is” and without warranty of any kind, either express or implied. The information is based on data believed to be reliable, but it is not guaranteed. Day Hagan DISCLAIMS ANY AND ALL EXPRESS OR IMPLIED WARRANTIES, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY, SUITABILITY, OR FITNESS FOR A PARTICULAR PURPOSE OR USE. All performance measures do not reflect tax consequences, execution, commissions, and other trading costs, and as such, investors should consult their tax advisors before making investment decisions, as well as realize that the past performance and results of the model are not a guarantee of future results. The Smart Sector® Strategy is not intended to be the primary basis for investment decisions, and the usage of the model does not address the suitability of any particular investment for any particular investor.
Using any graph, chart, formula, model, or other device to assist in deciding which securities to trade or when to trade them presents many difficulties, and their effectiveness has significant limitations, including that prior patterns may not repeat themselves continuously or on any particular occasion. In addition, market participants using such devices can impact the market in a way that changes the effectiveness of such devices. Day Hagan believes no individual graph, chart, formula, model, or other device should be used as the sole basis for any investment decision and suggests that all market participants consider differing viewpoints and use a weight-of-the-evidence approach that fits their investment needs.
Past performance does not guarantee future results. No current or prospective client should assume future performance of any specific investment or strategy will be profitable or equal to past performance levels. All investment strategies have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals, and economic conditions may materially alter the performance of your portfolio. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. Historical performance results for investment indexes and/or categories generally do not reflect the deduction of transaction and/or custodial charges or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing historical performance results. There can be no assurances that a portfolio will match or outperform any particular benchmark. Comparisons to indices are inherently unreliable indicators of future performance. The strategies used to generate the performance vary from those used to generate the returns depicted in the benchmarks. Investors cannot directly invest in an index.
The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
The material may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved. (© Copyright 2026 Day Hagan Asset Management.)
All hypothetical results are presented for illustrative purposes only. Back-testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
© 2026 Day Hagan Asset Management
Definitions:
S&P/ASX 200 – Designed to measure the performance of the 200 largest index-eligible stocks listed on the Australian Securities Exchange by float-adjusted market capitalization.
PMI — A survey-based economic indicator that measures business activity in sectors such as manufacturing and services; readings above 50 generally indicate expansion, while readings below 50 indicate contraction.
CPI — A measure of inflation that tracks changes in the prices consumers pay for goods and services over time.
Core Inflation — Inflation excluding more volatile items, typically food and energy, used to gauge underlying price trends.
Federal Reserve (Fed) — The central bank of the United States, responsible for monetary policy, interest rates, and financial stability.
ECB — The European Central Bank, responsible for setting monetary policy for countries that use the euro.
Bank of Japan (BoJ) — Japan’s central bank, responsible for monetary policy, interest rates, and financial conditions in Japan.
Bank of Canada (BoC) — Canada’s central bank, responsible for setting policy rates and managing inflation and economic stability.
Bank of England (BoE) — The United Kingdom’s central bank, responsible for monetary policy and financial stability.
SNB — The Swiss National Bank, responsible for monetary policy and maintaining price stability in Switzerland.
PBoC — The People’s Bank of China, which manages monetary policy, liquidity, and key lending benchmarks in China.
S&P 500 — A major U.S. stock market index tracking 500 large publicly traded U.S. companies; widely used as a benchmark for the U.S. equity market.
DJIA — The Dow Jones Industrial Average, a price-weighted stock index of 30 large U.S. companies, often used as a headline indicator of the U.S. stock market.
Nasdaq Composite — A stock market index composed largely of companies listed on the Nasdaq exchange, with especially heavy representation from technology and growth stocks.
STOXX 600 — A broad European stock index that tracks 600 large, mid, and small companies across Europe.
Nikkei 225 — A major Japanese stock market index tracking 225 prominent Japanese companies.
TSX — Canada’s main stock market benchmark, often referring to the S&P/TSX Composite Index.
CAC 40 — France’s main stock market index, tracking 40 major French companies.
DAX — Germany’s main stock market index, tracking major German listed companies.
FTSE 100 — The leading U.K. stock market index, tracking 100 large companies listed in London.
Shanghai Composite — A major Chinese stock index tracking stocks listed on the Shanghai Stock Exchange.
Shenzhen Component — A major Chinese stock index tracking companies listed on the Shenzhen Stock Exchange.
ACWI ex-U.S. Index — The MSCI All Country World Index excluding the United States; a benchmark for developed and emerging equity markets outside the U.S.
10-Year Yield — The interest rate paid on a 10-year government bond; a key benchmark for long-term borrowing costs and valuation.
Bund Yield — The yield on German government bonds, often used as a benchmark for euro-area sovereign debt.
Gilt Yield — The yield on U.K. government bonds, commonly called gilts.
OAT Yield — The yield on French government bonds.
Policy Rate — The benchmark interest rate set by a central bank to influence borrowing costs, inflation, and economic activity.
Basis Point (bp) — One one-hundredth of a percentage point; 25 basis points equals 0.25%.
Relative Strength — A measure of how a market, sector, or asset performs compared with another market or benchmark.
Overweight / Underweight / Neutral — Portfolio positioning terms: overweight means above benchmark allocation, underweight means below benchmark allocation, and neutral means roughly in line with the benchmark.