Day Hagan Smart Sector® International Strategy Update October 2026
A downloadable PDF copy of the Article:
Day Hagan Smart Sector® International Strategy Update October 2026 (pdf)
Executive Summary
We enter October overweight Japan, South Korea, Switzerland, and Taiwan. The Netherlands and the United Kingdom are neutral. Australia, Canada, China, France, Germany, and India are underweight. The portfolio continues to allocate approximately 85% of its equity holdings to Core markets and 15% to Explore markets. Mexico and Spain join the Explore sleeve, replacing Chile and Israel alongside continuing positions in the Philippines, Italy, and Thailand.
The latest manufacturing surveys support continued international growth, but the improvement is uneven. September factory PMIs reached 56.7 in Taiwan and 55.6 in the Netherlands. Japan remained in expansion at 54.1, while France slowed to 50.6. China's official manufacturing PMI recovered to 50.1. These readings help explain the economic backdrop, but a growing economy alone does not establish that its stock market will outperform. Our allocations also consider market trends, earnings, valuation, currency conditions, and investor behavior.
Policy became more restrictive in several important markets during September. The European Central Bank raised its deposit rate to 2.50%, the Bank of Japan increased its policy rate to 1.25%, and the Reserve Bank of Australia raised its cash rate to 4.60%. The Bank of England held at 3.75%, while the Swiss National Bank maintained a 0% policy rate. Higher financing costs and energy prices place a greater burden on companies to protect margins and deliver earnings.
Our overweight positions reflect different sources of support. Japan has stronger trend and valuation confirmation. South Korea and Taiwan retain favorable technical readings and exposure to semiconductor demand. Switzerland adds a market where momentum and relative income indicators have improved. The Netherlands remains neutral despite six bullish readings because its forward-earnings signal is still bearish.
China and India show why we evaluate more than the latest economic release. Their manufacturing surveys improved in September, yet most country indicators remain bearish. Australia's tighter policy and weaker factory conditions reinforce its move to underweight. Across Europe, better industrial activity has not overcome the unfavorable market evidence in France and Germany. Currency remains an important source of risk, particularly where the equity trend is stronger than the currency signal.
Economic and Policy Outlook
Industrial demand is improving, but the inflation and financing backdrop has become harder. The euro area's final manufacturing PMI increased to 52.9 in September from 52.7 in August. Japan, Korea, Taiwan, and the Netherlands also remained above 50. Demand linked to semiconductors, technology investment, and capital goods provides support for selected markets. The factory recovery is less uniform in consumer-facing industries and does not imply that all companies can recover higher costs through their selling prices.
Energy is the main cross-market pressure. The Middle East conflict and related supply and shipping disruptions have raised costs and uncertainty. Brent crude rose approximately 14% in September. Higher fuel and freight costs can squeeze margins, reduce household purchasing power, and lift the cost of imported goods. Commodity-producing markets may benefit through export receipts, while energy importers face a larger direct burden. Those advantages and disadvantages need to be assessed alongside each market's earnings, valuation, and currency signals.
Central banks have responded differently. The ECB, RBA, and Bank of Japan raised rates in September. The Bank of Korea had already raised its rate in August. The Bank of England held with a divided vote, while Switzerland and Taiwan maintained their existing settings. This divergence matters for international portfolios because a country's financing costs, exchange rate, and market valuation can respond differently to the same energy shock. A higher policy rate may support some banks' lending income while increasing debt-service costs and credit risk elsewhere.
The euro area's final August harmonized inflation rate was 3.2%, up from 2.9% in July. The earlier 3.3% August flash estimate was revised. September's area-wide inflation release was not yet available at this letter's cutoff, so it is not treated as reported data. Preliminary September national readings nevertheless show renewed pressure in France, Germany, Italy, and Spain. Policymakers must judge whether energy costs remain concentrated or feed more broadly into wages and prices. Further tightening is a risk rather than an outcome we assume.
Our response is to maintain greater relative exposure where market evidence supports the economic opportunity. Japan, Korea, and Taiwan offer improving industrial activity alongside favorable trend readings. Switzerland provides a different mix of international businesses, relative income support, and less restrictive monetary policy. We keep the Netherlands and U.K. neutral where supportive evidence is offset by earnings or currency concerns. Underweights in Australia, Canada, China, France, Germany, and India reflect weaker overall relative evidence, even where individual economic releases may be improving.
The central risk to this positioning is that industrial strength fails to deliver the profits investors expect, or that energy costs and higher rates spread into a broader demand slowdown. A stronger dollar can also reduce U.S.-dollar returns on foreign holdings even when local share prices rise. We will respond to changes in the models rather than presume a quick geopolitical resolution or a uniform global rate cycle.
Holdings
Core: Developed Market Positions (approximately 85% of equity holdings)
Country
Australia
Canada
China
France
Germany
India
Japan
Netherlands
South Korea
Switzerland
Taiwan
United Kingdom
Outlook
Underweight
Underweight
Underweight
Underweight
Underweight
Underweight
Overweight
Neutral
Overweight
Overweight
Overweight
Neutral
Explore: Emerging Market Positions (approximately 15% of equity holdings)
Philippines
Italy
Mexico
Spain
Thailand
Position Details
Core: Developed Market Commentary
Position Details
Core Developed Market Commentary
Approximately 85% of the strategy is allocated across 12 large, liquid non-U.S. equity markets. The fund overweights and underweights these markets based on macro, fundamental, behavioral, currency, and technical indicators. The discussion below reflects information available through September 30, 2026.
AUSTRALIA — UNDERWEIGHT
Australia moves to underweight as its market evidence weakens and monetary policy becomes more restrictive. The adaptive trend, beta relationship, and relative earnings yield remain supportive. The absolute moving-average cross, gold comparison, Australia-U.S. interest-rate differential, and global technical scorecard are bearish.
September's manufacturing PMI registered 49.6, below the expansion threshold. The Reserve Bank of Australia raised the cash rate by 25 basis points to 4.60% on September 29. We see a difficult combination for domestic businesses when borrowing costs rise while factory conditions weaken. Resource companies can still benefit from global commodity demand, but that opportunity does not offset the broader deterioration in country signals. The underweight retains participation while reducing exposure to an economy facing tighter financing conditions.
Inflation adds to that constraint. Australia's CPI rose 4.0% over the year to August, up from 3.5% in July. Trimmed-mean inflation was 3.6%, showing that price pressure extends beyond the most volatile components. The housing component of CPI rose 5.7% over the year. The RBA's September increase therefore addresses persistent domestic inflation as well as the risk from energy costs. Higher borrowing costs can restrain household purchases, construction, and business investment even when commodity exporters benefit from higher selling prices.
Tighter domestic policy and weaker manufacturing conditions reinforce the case for the underweight. A stronger resource cycle would be helpful, but a broader improvement in relative performance would carry more weight in the allocation decision. The earnings-yield signal provides some valuation support and keeps us from treating the country as uniformly unattractive.
Figure 1: Australia’s mixed trend signals and weaker technical confirmation support an underweight despite favorable relative earnings yield.
CANADA — UNDERWEIGHT
Canada remains underweight. Moving-average diffusion, the global technical scorecard, and the Canadian-dollar relationship provide support. Mean reversion, the absolute moving-average cross, the OECD leading indicator, and relative earnings yield remain unfavorable.
The September manufacturing PMI declined to 51.5 from 53.0 in August, indicating continued expansion at a slower pace. The Bank of Canada maintained its policy rate at 2.25% on September 2. Trade friction and elevated energy costs complicate the outlook, even though some Canadian producers benefit from higher commodity prices. Better currency and technical readings are encouraging, but the combination of weaker industrial momentum and bearish leading and valuation signals leaves us underweight.
Recent activity data also argue for restraint in Canada. Real GDP was unchanged in July after three months of growth. Statistics Canada's advance estimate pointed to a 0.2% increase in August, but that estimate is preliminary. The combination suggests modest expansion rather than a decisive acceleration. August CPI inflation held at 3.0%, while inflation excluding gasoline rose to 2.4% from 2.2%. Gasoline prices were 22.8% higher than a year earlier, illustrating the pressure energy costs can place on purchasing power.
Higher commodity prices can support Canadian producers and export receipts, but they also raise costs for households and nonenergy businesses. Exposure to U.S. demand and trade policy adds uncertainty for manufacturers. We retain the underweight because these offsets, slower survey growth, and the unfavorable leading and earnings-yield signals leave the relative investment case incomplete. The bullish currency relationship is useful support, but it does not resolve the broader weakness.
Figure 2: Canada’s improving breadth and currency signals have not overcome weakness in leading indicators and relative valuation.
CHINA — UNDERWEIGHT
China moves to underweight following a substantial reversal in its indicator mix. The PMI signal is bullish, and the bear-market-bounce measure is neutral. Relative price momentum, mean reversion, the absolute moving-average cross, the emerging-market currency relationship, and high-yield credit-spread signal all argue for caution.
The official manufacturing PMI rose to 50.1 in September from 49.8 in August. The private RatingDog manufacturing survey also improved to 52.1. That is welcome evidence of firmer factory conditions. However, the stronger survey readings have not been accompanied by favorable confirmation from most of our equity, currency, and credit indicators. We need broader improvement before assigning more capital. The underweight reflects the market's relative evidence while leaving room to respond if the recovery gains support.
China's August hard data show a wider gap between production and domestic demand. Industrial output rose 5.2% from a year earlier, while retail sales increased only 0.4%. Fixed-asset investment fell 7.2% over January through August compared with the same period last year. Those measures cover different periods, but together they show why a better manufacturing PMI should not be read as a full recovery in household spending and investment.
August consumer inflation was 0.8% and core inflation was 1.0%, while producer prices rose 3.8%. That divergence raises questions about manufacturers' ability to pass higher costs through to customers. September loan prime rates remained 3.00% for one-year loans and 3.50% for five-year loans. Policy support can help financing conditions, but it cannot by itself repair demand or corporate balance sheets. We favor the underweight until the improvement in factory surveys is joined by stronger consumer activity and better relative equity and credit evidence.
Figure 3: China’s stronger manufacturing signal has yet to produce broader equity, currency, and credit confirmation.
FRANCE — UNDERWEIGHT
France remains underweight, with fund flows the only bullish reading. The moving-average cross, market breadth, global technical scorecard, 50-day momentum, leading indicator, relative dividend yield, and valuation scorecard are unfavorable. The weakness extends beyond a single economic or market measure.
The final September manufacturing PMI fell to 50.6 from 51.1 in August. Factory output increased, but new orders declined for a fifth consecutive month. The ECB's September increase brought its deposit rate to 2.50%, adding financing pressure to an already uncertain demand outlook. We view the modest factory expansion as insufficient evidence to increase the allocation while orders and most country indicators remain weak.
France's preliminary September national CPI inflation rose to 3.0% from 2.4% in August. The harmonized measure was 3.4%, up from 2.6%. Energy prices increased 21.2% from a year earlier. These are preliminary readings, but the direction is clear: households and businesses face a renewed cost burden just as factory orders are weakening. The national and harmonized indices use different methods and should not be interchanged.
Higher energy costs, a higher ECB policy rate, and pressure on public finances reduce the room to offset weak private demand. Companies with international revenue can perform differently from the domestic economy, but the bearish valuation and dividend-yield readings provide little support for increasing country exposure. We retain the underweight. Positive fund flows are worth monitoring, but stronger buying activity alone is not enough when price trends, breadth, and orders remain unfavorable.
Figure 4: Seven bearish indicators support France’s underweight, with modestly positive fund flows providing the only favorable reading.
GERMANY — UNDERWEIGHT
Germany remains underweight, although August delivered the strongest challenge yet to that view. The Germany remains underweight despite continued manufacturing expansion. The final September factory PMI was 53.9, down from 54.3 in August. Production and new orders continued to grow, but higher energy costs and supply delays remained concerns. The ECB's increase to a 2.50% deposit rate also raises the cost of financing investment and working capital.
Only two indicators are currently bullish. Breadth and relative dividend yield are constructive, while the bear-market-bounce signal is neutral. The global technical scorecard, relative moving-average cross, fund flows, manufacturing-confidence relationship, and euro signal are bearish. The PMI recovery deserves attention, but we want it accompanied by stronger relative price behavior and broader market confirmation. For now, the underweight remains appropriate within the October allocation.
Germany's preliminary September CPI and harmonized inflation readings were both 3.3%, up from 2.9% in August. Energy inflation accelerated to 14.9% from 10.5%. Core CPI inflation remained 2.4%, which suggests that the immediate increase was concentrated in energy rather than a comparable acceleration across all prices. The distinction matters for policy, but energy still affects industrial costs and households' ability to spend.
Germany's improving factory survey is a reason to retain exposure, especially to globally competitive industrial businesses. It is less persuasive as a reason to overweight when financing costs are rising and the relative trend, flows, and currency readings remain bearish. Energy-intensive companies face particular pressure if higher costs cannot be recovered through prices. We favor the underweight while looking for the production recovery to produce broader earnings and market confirmation.
Figure 5: Germany’s favorable breadth and dividend-yield readings remain insufficient to offset weaker trend, confidence, currency, and flow signals.
INDIA — NEUTRAL
India moves to underweight even as its factory survey improves. September's manufacturing PMI rose to 55.1 from 52.8 in August, pointing to stronger business conditions. The improvement supports the economic case, but our equity-market framework remains unfavorable. Six of eight readings are bearish, the absolute moving-average cross is neutral, and the gold relationship is the only bullish signal.
Mean reversion, the global technical scorecard, the rupee, crude oil, forward earnings growth, and the OECD leading indicator all weigh on the allocation. India's sensitivity to imported energy makes the oil and currency signals particularly relevant to costs and purchasing power. Stronger manufacturing demand is encouraging, but the underweight recognizes that economic growth, earnings delivery, and relative stock-market performance can move on different schedules.
Inflation is becoming a more immediate constraint in India. August retail CPI inflation reached 4.82%, up from 4.45% in July. The RBI held its repo rate at 5.25% in August. A subsequent rate increase would be a future policy decision, not an established fact at this letter's cutoff. Rising oil costs and rupee weakness can increase the local-currency cost of imports, which complicates the balance between supporting growth and containing inflation.
India can continue to expand while its equities underperform other markets. The bullish factory survey supports that distinction, while the bearish forward-earnings, oil, and currency readings make the investment hurdle higher. Reduced relative exposure remains appropriate until growth is accompanied by better earnings and price confirmation. This is a relative allocation decision, not a forecast of recession or a rejection of India's longer-term economic potential.
Figure 6: India’s stronger factory activity contrasts with unfavorable earnings, currency, and technical signals, supporting an underweight.
NETHERLANDS — NEUTRAL
The Netherlands remains neutral, with absolute trend, mean reversion, the global technical scorecard, semiconductors, the euro relationship, and the OECD leading indicator supporting exposure. Forward earnings growth remains a headwind.
The September manufacturing PMI rose to 55.6 from 53.8 in August, with faster growth in new orders and production. That supports the industrial backdrop for a market with important exposure to semiconductor equipment and other global businesses. At the same time, stronger activity and market trends have yet to produce a favorable forward-earnings signal. The neutral allocation preserves exposure to the improving cycle while recognizing that earnings expectations still need confirmation. The ECB's higher deposit rate adds another reason to monitor financing costs and valuation sensitivity.
The Dutch survey's strength is meaningful: September production growth was the fastest since January 2022. However, household inflation also increased. National CPI inflation reached 3.3% in August, compared with 3.2% in July. The harmonized rate was 2.8%. These are different measures, and the national rate is the one used here to describe domestic purchasing-power pressure.
We retain neutral exposure because the favorable industrial cycle and broad indicator support are balanced by the bearish forward-earnings signal. Semiconductor equipment demand can sustain activity, but concentrated exposure also increases sensitivity to customer spending plans, trade restrictions, and changes in earnings expectations. Higher ECB rates raise the hurdle for capital investment and growth-stock valuations. An overweight would require a stronger overall case that earnings can meet expectations, rather than simply a higher PMI.
Figure 7: Six bullish indicators support continued Dutch exposure, but weaker forward-earnings confirmation tempers the case for an overweight.
SOUTH KOREA — OVERWEIGHT
South Korea remains overweight with absolute trend, mean reversion, the global technical scorecard, and the won relationship constructive. Crude oil, forward earnings growth, and the OECD leading indicator remain bearish.
September's manufacturing PMI rose to 53.9 from 52.3 in August. Stronger semiconductor and auto demand supported production and new orders, while export orders accelerated. Those developments reinforce the favorable market signals. The risk is that better operating conditions may still fall short of investor expectations, particularly when the earnings indicator remains bearish. Korea also imports energy, leaving margins exposed to oil prices. We retain the overweight while watching whether stronger demand translates into improving earnings estimates.
September trade data strengthen Korea's operating case. Preliminary exports rose 83.5% from a year earlier to $120.9 billion, with semiconductor exports reaching $60.3 billion. Chips accounted for roughly half of total exports. These are nominal trade values, not measures of real GDP growth, and higher prices can contribute to the increase. Even with that qualification, the data show how central semiconductor demand has become to the economy and its equity market.
Policy has tightened alongside that strength. The Bank of Korea raised its base rate to 3.00% in August and increased its 2026 growth forecast to 3.3% from 2.6%. August CPI inflation rose to 3.1% from 2.8%, partly reflecting a comparison with temporary mobile-service discounts a year earlier. We favor the overweight because stronger orders and exports reinforce the bullish technical and currency readings. Higher rates, energy dependence, and the bearish earnings signal remain reasons to watch whether the export surge produces sustainable profit growth.
Figure 8: South Korea’s favorable technical and currency signals support an overweight, with earnings and economic-leading indicators still requiring confirmation.
TAIWAN — OVERWEIGHT
Absolute trend, mean reversion, the global technical scorecard, the semiconductor relationship, and valuation are supportive. The China PMI relationship and Taiwan-dollar signal are bearish.
The September manufacturing PMI reached 56.7, providing additional confirmation of stronger operating conditions. At its September meeting, Taiwan's central bank maintained the benchmark discount rate at 2.00%. The combination of industrial growth and steady policy supports the backdrop, although equity returns still depend on earnings, expectations, and currency translation. Taiwan's semiconductor concentration remains a material risk. The overweight recognizes broad model support while keeping the weaker currency and China-related readings in view.
Taiwan's central bank raised its 2026 growth forecast to 11.48% at the September meeting and projected inflation of 2.03%. Those are forecasts, not realized annual results. Together with the 56.7 manufacturing PMI, they support an outlook of strong industrial activity without a comparable surge in expected consumer inflation. The unchanged discount rate provides a more stable financing backdrop than the recent rate increases in Japan and Korea.
We favor the overweight because the semiconductor, trend, technical, and valuation signals point in the same direction. Concentration is also the principal vulnerability. A reduction in technology investment, an earnings disappointment, export restrictions, or disruption across the Taiwan Strait could have a disproportionate effect on the market. The bearish Taiwan-dollar and China-PMI relationships add caution. Strong industry demand supports the allocation, but it does not eliminate those risks or ensure that market expectations will be met.
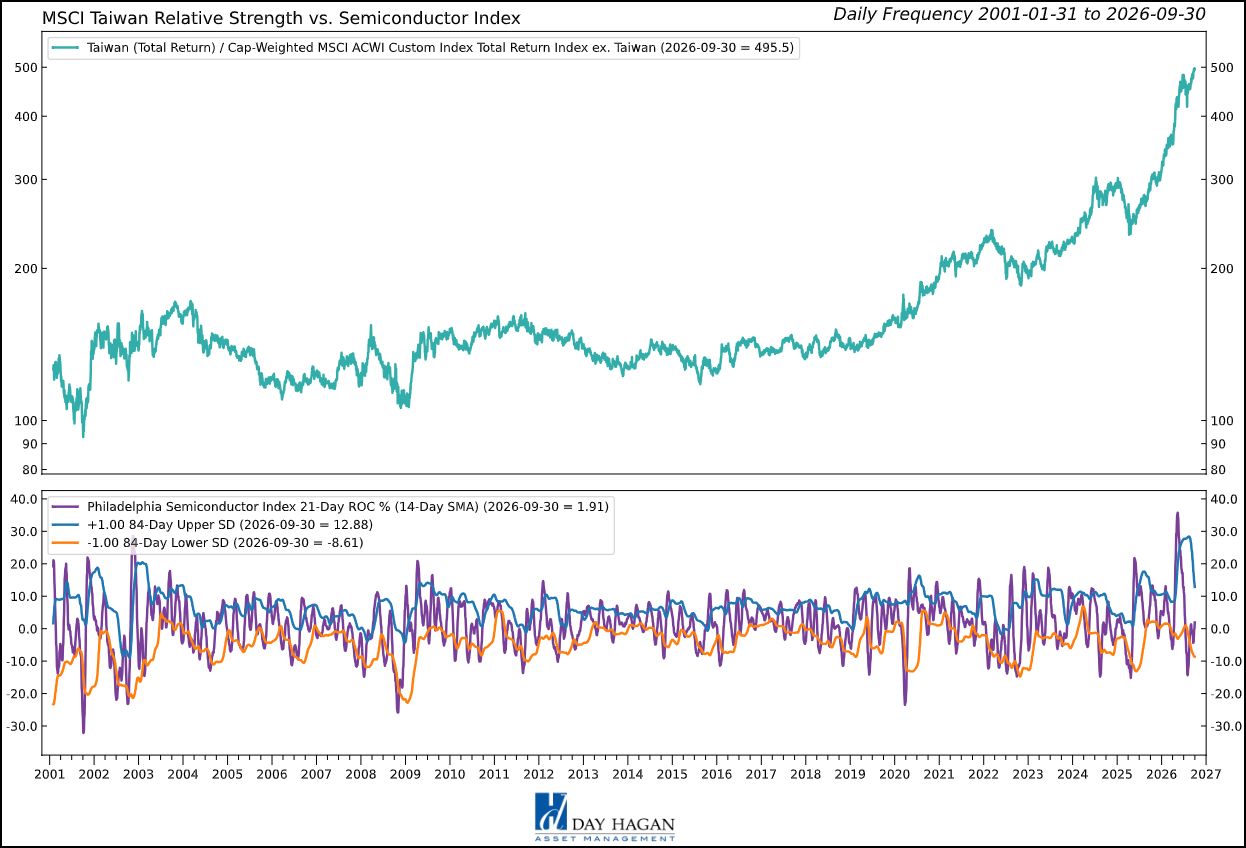
Figure 9: Taiwan’s favorable trend, semiconductor, and valuation signals support an overweight despite weaker currency and China-related readings.
JAPAN — OVERWEIGHT
Japan moves to overweight as absolute and relative moving-average trends, the global technical scorecard, the China PMI relationship, and valuation are bullish. Forward earnings growth, sentiment reversals, and the yen relationship remain bearish. The favorable signals support a larger allocation, while the remaining warnings limit conviction.
Japan's September manufacturing PMI was 54.1, down from 54.9 in August but still indicating expansion. The Bank of Japan raised its policy rate to 1.25% in September. Higher rates can improve lending margins for banks, while increasing financing costs elsewhere. Currency movements also affect exporter profits and returns translated into U.S. dollars. The overweight rests on stronger market trends and valuation evidence, with close attention to earnings and the yen as policy continues to adjust.
The Bank of Japan's September Tankan survey, released October 1, adds evidence beyond the monthly PMI. Confidence among large manufacturers improved to +24 from +22 in June. Large nonmanufacturers' confidence eased to +35 from +37, and both groups expected conditions to worsen over the next three months. Positive readings indicate that favorable assessments still outnumber unfavorable ones. The survey supports industrial resilience while showing that the recovery is uneven.
Japan's higher policy rate reflects a different environment from the long period of near-zero borrowing costs. Banks may benefit from higher lending yields, but borrowers face more expensive financing and exporters remain sensitive to the yen. Energy imports are another source of margin risk. The overweight has a stronger basis now that favorable trend and valuation readings are accompanied by solid manufacturing sentiment. The bearish earnings and currency signals argue for disciplined sizing rather than assuming that improved business confidence guarantees stronger equity returns.
Figure 10: Japan’s stronger trends and favorable valuation support an overweight, while earnings, sentiment, and currency signals remain cautionary.
SWITZERLAND — UNDERWEIGHT
Switzerland moves to overweight as shorter-term price momentum, the slope of relative strength, relative dividend yield, and the relative 10-year-yield measure are rated positive. The moving-average cross and 200-day breadth remain bearish, while fund flows are neutral.
The Swiss National Bank maintained its policy rate at 0% on September 24 and reiterated its willingness to intervene in currency markets when necessary. That policy setting differs markedly from the September tightening in Australia, Japan, and the euro area. Switzerland offers exposure to globally diversified healthcare, consumer, industrial, and financial businesses. Improved momentum and relative income signals support the larger allocation, but weak breadth indicates that participation remains incomplete. The franc also needs attention because appreciation can help U.S.-dollar returns while pressuring exporters' translated revenue.
The SNB's September assessment reported August inflation of 0.8%, compared with 0.6% in May. Its conditional inflation forecast was 0.7% for 2026 and 0.8% for 2027, based on an unchanged 0% policy rate. The bank expected GDP growth of 1.5% to 2.0% in 2026. These are policy forecasts, not reported full-year outcomes. They indicate a less restrictive inflation backdrop than in several other developed markets.
The SNB also noted that recent franc depreciation had supported activity. That can help exporters' competitiveness, while creating a different effect on returns measured in U.S. dollars. We favor the overweight because improved momentum and relative income signals offer a useful complement to the portfolio's technology-oriented markets. Switzerland's internationally exposed businesses still face global demand, currency, and valuation risks. Weak breadth is the main reason to seek wider participation before becoming more confident in the advance.
Figure 11: Improving Swiss momentum and relative income signals support an overweight, although broader trend participation indicates near-term caution is warranted.
UNITED KINGDOM — NEUTRAL
The United Kingdom moves to neutral with an even split between bullish and bearish readings. Price momentum, valuation, and the credit-spread relationship are bullish. The moving-average cross, sterling relationship, and sentiment measure are bearish. The change reflects reduced confirmation from the currency alongside a still-supportive valuation signal.
The Bank of England held Bank Rate at 3.75% in September by a 6-3 vote, with three members favoring an increase to 4.00%. It reported August inflation of 3.1% and warned that higher energy prices could keep inflation elevated. September's manufacturing survey also highlighted renewed cost pressure. The U.K. market's international businesses provide exposure beyond domestic demand, but tighter financing conditions and unfavorable sterling and sentiment readings support a neutral allocation.
The split vote at the Bank of England shows why a rapid easing cycle should not be assumed. Three policymakers favored a quarter-point increase even though the majority held rates. The bank's September assessment warned that higher energy costs could lift inflation in coming quarters. That raises the risk of a longer period of restrictive financing conditions, with different consequences for lenders, indebted businesses, and consumers.
We favor neutral exposure because valuation and momentum provide a reason to participate, while sterling, sentiment, and the moving-average cross limit the case for a larger weight. International revenue can cushion weakness in domestic activity, but it also makes currency translation important to reported earnings. A softer pound may help some companies' foreign revenue while reducing dollar-based investment returns. The allocation allows participation without treating low valuation alone as sufficient evidence of outperformance.
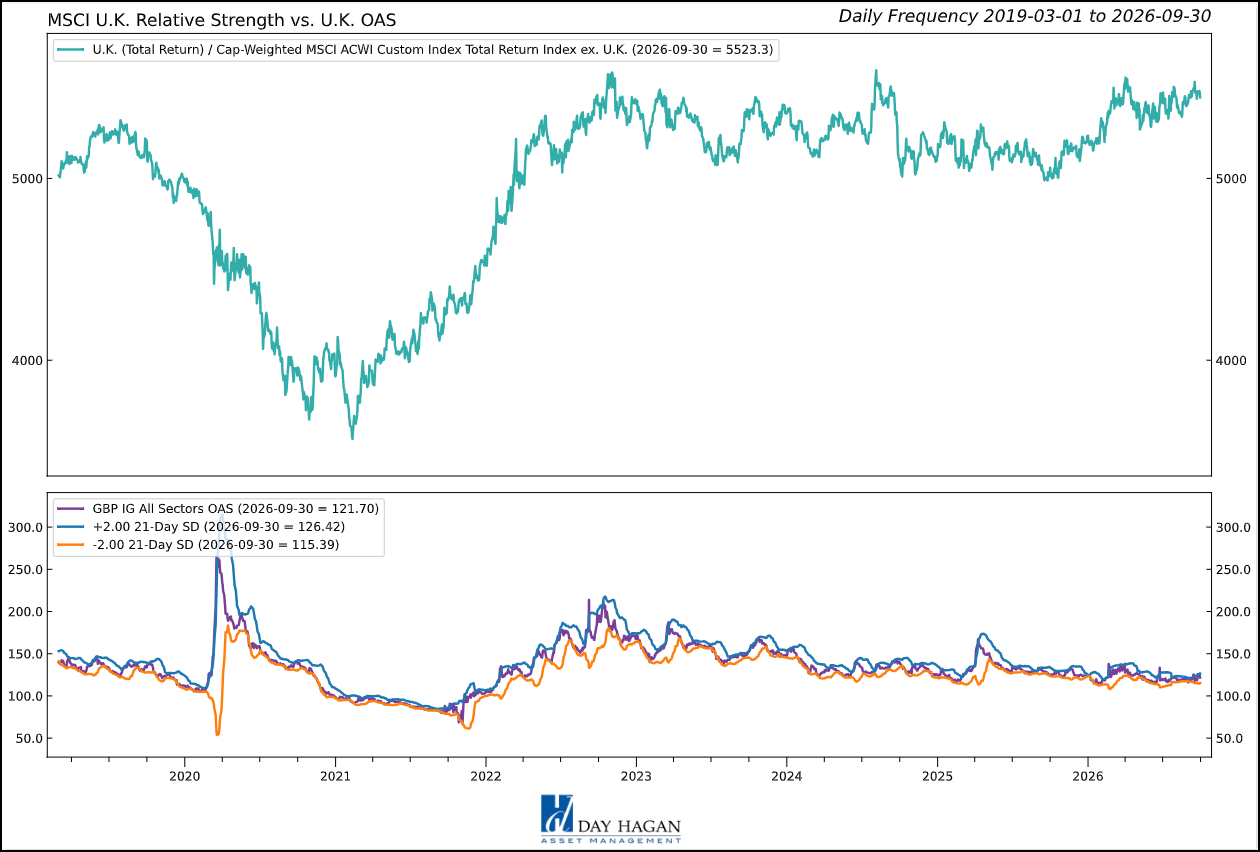
Figure 12: The U.K.’s favorable momentum, valuation, and credit signals are offset by weaker trend, currency, and sentiment readings.
Emerging Market Positions
Approximately 15% of the strategy is allocated across five markets from a pool of more than 20 smaller markets. Selection is based on a multifactor technical ranking system that uses trend and mean-reversion indicators. The process seeks to identify oversold opportunities likely to mean-revert and modest pullbacks within longer-term uptrends. These positions can be more volatile and less liquid than the core allocation.
Current Holdings
Philippines
Italy
Mexico
Spain
Thailand
Explore Emerging Market Commentary
Philippines
The Philippines position provides exposure to a market with banks, property, utilities, and consumer businesses. A recovery in demand could improve earnings, while imported energy costs, currency weakness, and credit conditions remain risks.
The Philippines faces a difficult inflation backdrop. August CPI inflation was 6.1%, only slightly below July's 6.2%. The central bank's target reverse-repurchase rate was 5.00% entering October. Elevated inflation and financing costs can weigh on household demand and property activity, while imported fuel costs leave the economy exposed to renewed energy-price increases.
More durable participation would be easier to support if factory orders stabilize and inflation declines enough to improve purchasing power. Energy subsidies or other price relief may reduce the immediate burden, but they would not necessarily resolve the underlying cost pressure.
Italy
Italy remains in the Explore sleeve as its manufacturing PMI improved to 50.4 in September from 49.6 in August. The headline returned above 50, but output and new orders still declined slightly. That distinction matters because a better composite survey can coexist with weak demand.
The market offers exposure to banks, insurers, industrial businesses, and energy infrastructure. The ECB's 2.50% deposit rate can support some lenders' income while increasing financing costs and credit risk. We see a tactical opportunity that still requires better order growth and careful attention to the effect of higher rates.
Italy's preliminary September national CPI inflation rose to 4.2% from 3.3% in August. The harmonized measure was 4.1%. The price acceleration increases the burden on consumers and manufacturers just as the PMI's order and output components remain weak. It also complicates the government's response because additional relief spending must be balanced against public-finance constraints.
For industrial companies, a sustained recovery in orders would be more convincing than a headline PMI just above 50. The position reflects relative technical opportunity, with the inflation and demand backdrop limiting the fundamental case.
Mexico
Mexico joins the Explore sleeve. Its manufacturing links to the United States create potential opportunities from supply-chain investment, while also exposing the market to tariffs and shifts in U.S. demand. Banks, consumer companies, and industrial businesses provide additional sources of earnings.
The Bank of Mexico held its benchmark rate at 6.50% on September 24 and removed language suggesting a prolonged pause. It will weigh inflation, exchange-rate effects, economic slack, and expectations in future decisions. That leaves room for policy adjustment without establishing a direction or timetable. The position reflects the technical ranking, with currency and trade policy central to the risk assessment.
Mexico's August manufacturing PMI was 49.8, down from 51.3 in July. August CPI inflation increased to 3.26% from 3.12%, while core inflation eased to 3.88% from 3.95%. The distinction is useful: headline price pressure increased, but the underlying measure did not accelerate in the same way. The 6.50% policy rate remains a material financing cost for businesses and households.
Supply-chain investment and U.S. industrial demand offer potential support, while tariffs, trade negotiations, and peso movements can change the earnings outlook quickly. Banxico's decision leaves future adjustments dependent on the data. Neither a rate cut nor a recovery in manufacturing should be treated as assured.
Spain
Spain joins the Explore sleeve as September's manufacturing PMI rose to 51.0 from 49.5 in August. Production improved and export orders increased, although total new orders continued to decline. The survey supports a possible recovery.
Banks, utilities, infrastructure, and tourism-related businesses broaden the market's earnings base. Higher ECB rates can affect those industries differently, supporting some lending income while raising financing costs for borrowers. The Explore position provides tactical participation while we monitor whether better production develops into more durable order growth.
Spain's preliminary September national CPI inflation rose to 4.9% from 4.3% in August. Core inflation increased to 3.1% from 2.9%, and harmonized inflation was 5.0%. Unlike a price increase concentrated entirely in energy, the rise in core inflation suggests a wider cost burden. Higher household expenses can reduce discretionary spending, while higher rates affect construction, property, and other financed activity.
Tourism and internationally exposed businesses offer additional earnings sources, but transport costs and weaker consumers can affect them as well. We would view broader order growth as stronger confirmation than another small increase in the headline PMI.
Thailand
Thailand remains an Explore holding with a firmer manufacturing backdrop. The September PMI rose to 54.3 from 53.8 in August, supported by faster growth in output and new orders. That provides useful economic support for the technical selection.
The market offers exposure to manufacturing, tourism, healthcare, and domestic financial businesses. Continued demand growth could improve earnings, but household credit quality, energy costs, and currency movements remain important. A stronger baht can help dollar-based returns while reducing the local-currency value of exporters' foreign sales. We will watch whether the factory improvement broadens to other parts of the economy.
August factory output rose 4.44% from a year earlier, adding a hard-data measure to Thailand's stronger manufacturing survey. The Bank of Thailand maintained a 1.00% policy rate in August. In September, a central-bank official reiterated growth forecasts of 2.3% for 2026 and 1.8% for 2027. Those forecasts describe a subdued broader economy despite the recent factory gains.
Stronger output and orders support retaining Thailand's tactical position. Low interest rates provide some support for activity, but high household debt and weak domestic demand can limit the response. Tourism, exports, and domestic consumption need not recover together.
Catastrophic Stop Model
The Catastrophic Stop model combines time-tested, objective indicators designed to identify high-risk periods for the equity market. The model entered October recommending a fully invested equity allocation relative to the benchmark.
The weight of the evidence suggests that international equity exposure can remain selective and fully invested at this time. If the model triggers a sell signal below 40% for two consecutive days, indicating more substantial market stress, the strategy will raise cash in accordance with its rules. The signal is systematic and may change as market conditions evolve.
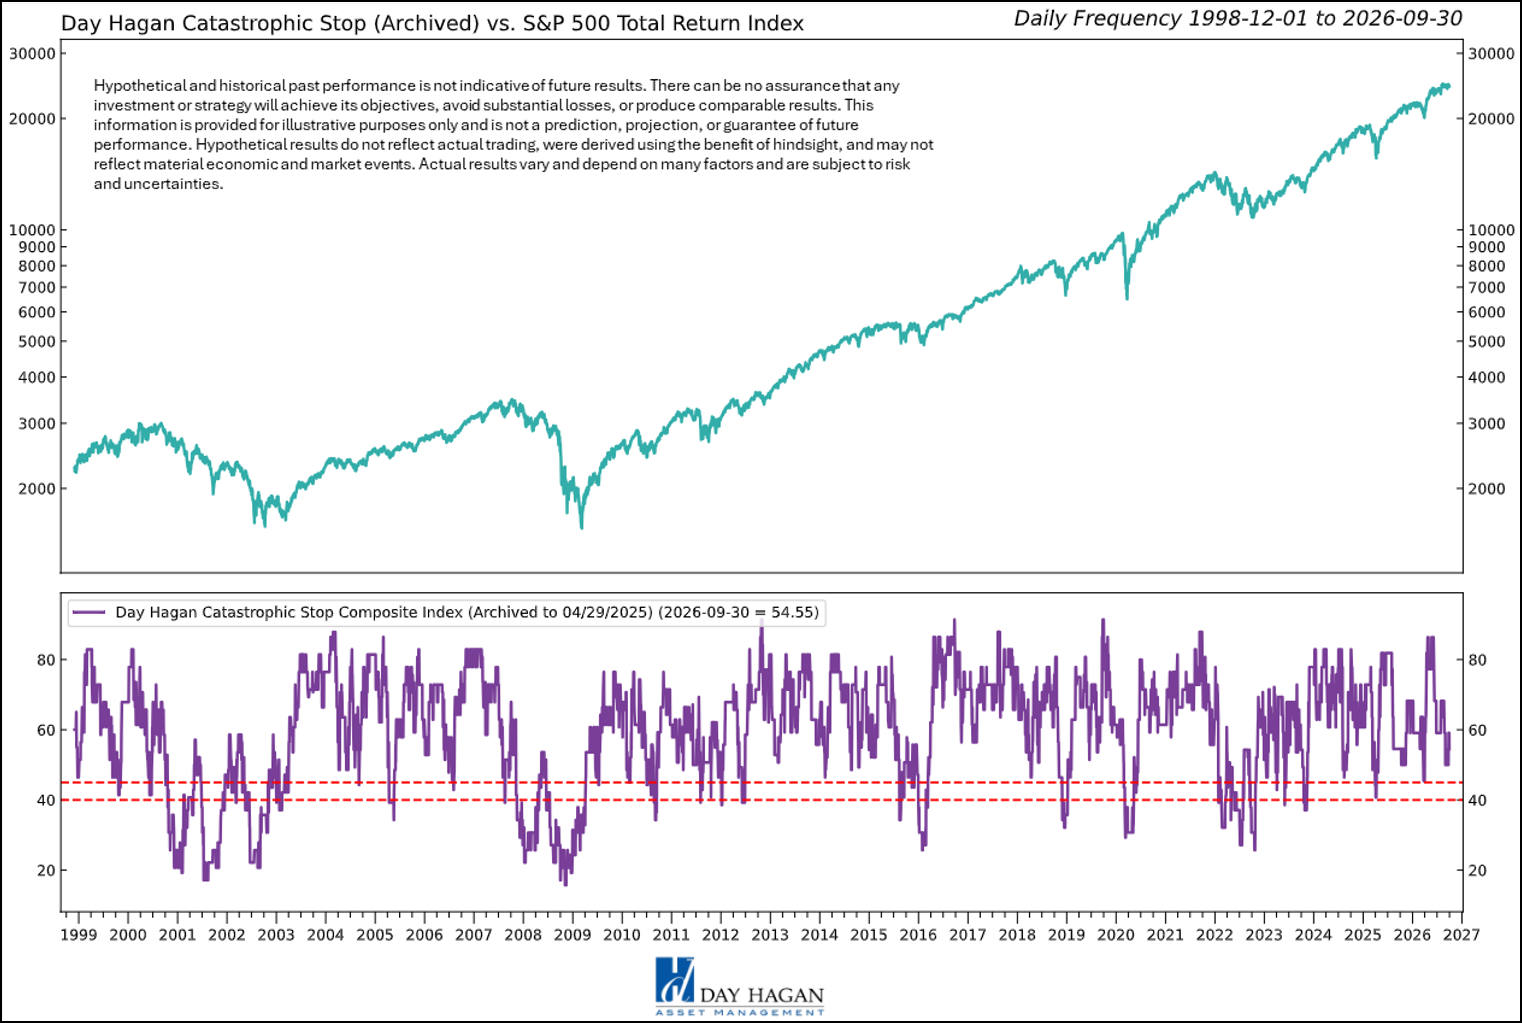
Figure 13: The Catastrophic Stop model recommends a fully invested equity position relative to the benchmark.
This strategy uses measures of price, valuation, economic trends, liquidity, and market sentiment to make objective, rational, and unemotional decisions about how much capital to risk and where to allocate it.
For more information, please contact us at:
Day Hagan Asset Management
1000 S. Tamiami Trl
Sarasota, FL 34236
Toll Free: (800) 594-7930
Office Phone: (941) 330-1702
Website: https://dayhagan.com or https://dhfunds.com
© 2026 Day Hagan Asset Management
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved. (© Copyright 2026 Day Hagan Asset Management.)
Day Hagan Smart Sector® International ETF
Symbol: SSXU
Disclosures
The data and analysis contained within are provided “as is” and without warranty of any kind, either express or implied. The information is based on data believed to be reliable, but it is not guaranteed. Day Hagan DISCLAIMS ANY AND ALL EXPRESS OR IMPLIED WARRANTIES, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY, SUITABILITY, OR FITNESS FOR A PARTICULAR PURPOSE OR USE. All performance measures do not reflect tax consequences, execution, commissions, and other trading costs, and as such, investors should consult their tax advisors before making investment decisions, as well as realize that the past performance and results of the model are not a guarantee of future results. The Smart Sector® Strategy is not intended to be the primary basis for investment decisions, and the usage of the model does not address the suitability of any particular investment for any particular investor.
Using any graph, chart, formula, model, or other device to assist in deciding which securities to trade or when to trade them presents many difficulties, and their effectiveness has significant limitations, including that prior patterns may not repeat themselves continuously or on any particular occasion. In addition, market participants using such devices can impact the market in a way that changes the effectiveness of such devices. Day Hagan believes no individual graph, chart, formula, model, or other device should be used as the sole basis for any investment decision and suggests that all market participants consider differing viewpoints and use a weight-of-the-evidence approach that fits their investment needs.
Past performance does not guarantee future results. No current or prospective client should assume future performance of any specific investment or strategy will be profitable or equal to past performance levels. All investment strategies have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals, and economic conditions may materially alter the performance of your portfolio. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. Historical performance results for investment indexes and/or categories generally do not reflect the deduction of transaction and/or custodial charges or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing historical performance results. There can be no assurances that a portfolio will match or outperform any particular benchmark. Comparisons to indices are inherently unreliable indicators of future performance. The strategies used to generate the performance vary from those used to generate the returns depicted in the benchmarks. Investors cannot directly invest in an index.
The information contained herein is provided for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. The securities, instruments, or strategies described may not be suitable for all investors, and their value and income may fluctuate. Past performance is not indicative of future results, and there is no guarantee that any investment strategy will achieve its objectives, generate profits, or avoid losses.
This material is intended to provide general market commentary and should not be relied upon as individualized investment advice. Investors should consult with their financial professional before making any investment decisions based on this information.
The material may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections, forecasts, estimates of market returns, and proposed or expected portfolio composition. Day Hagan Asset Management, its affiliates, employees, or third-party data providers shall not be liable for any loss sustained by any person relying on this information. All opinions and views expressed are subject to change without notice and may differ from those of other investment professionals within Day Hagan Asset Management or Ashton Thomas Private Wealth, LLC.
Accounts managed by Day Hagan Asset Management or its affiliates may hold positions in the securities discussed and may trade such securities without notice.
Day Hagan Asset Management is a division of and doing business as (DBA) Ashton Thomas Private Wealth, LLC, an SEC-registered investment adviser. Registration with the SEC does not imply a certain level of skill or training.
This material is for educational purposes only. Further distribution is prohibited without prior permission. Please see the information on Disclosures and Fact Sheets here: https://dhfunds.com/literature. Charts with models and return information use indices for performance testing to extend the model histories, and they should be considered hypothetical. All Rights Reserved. (© Copyright 2026 Day Hagan Asset Management.)
All hypothetical results are presented for illustrative purposes only. Back-testing and other statistical analysis is provided in use simulated analysis and hypothetical circumstances to estimate how it may have performed prior to its actual existence. The results obtained from "back-testing" information should not be considered indicative of the actual results that might be obtained from an investment or participation in a financial instrument or transaction referencing the Index. The Firm provides no assurance or guarantee that the products/securities linked to the strategy will operate or would have operated in the past in a manner consistent with these materials. The hypothetical historical levels have inherent limitations. Alternative simulations, techniques, modeling or assumptions might produce significantly different results and prove to be more appropriate. Actual results will vary, perhaps materially, from the simulated returns presented.
© 2026 Day Hagan Asset Management
Definitions:
S&P/ASX 200 – Designed to measure the performance of the 200 largest index-eligible stocks listed on the Australian Securities Exchange by float-adjusted market capitalization.
PMI — A survey-based economic indicator that measures business activity in sectors such as manufacturing and services; readings above 50 generally indicate expansion, while readings below 50 indicate contraction.
CPI — A measure of inflation that tracks changes in the prices consumers pay for goods and services over time.
Core Inflation — Inflation excluding more volatile items, typically food and energy, used to gauge underlying price trends.
Federal Reserve (Fed) — The central bank of the United States, responsible for monetary policy, interest rates, and financial stability.
ECB — The European Central Bank, responsible for setting monetary policy for countries that use the euro.
Bank of Japan (BoJ) — Japan’s central bank, responsible for monetary policy, interest rates, and financial conditions in Japan.
Bank of Canada (BoC) — Canada’s central bank, responsible for setting policy rates and managing inflation and economic stability.
Bank of England (BoE) — The United Kingdom’s central bank, responsible for monetary policy and financial stability.
SNB — The Swiss National Bank, responsible for monetary policy and maintaining price stability in Switzerland.
PBoC — The People’s Bank of China, which manages monetary policy, liquidity, and key lending benchmarks in China.
S&P 500 — A major U.S. stock market index tracking 500 large publicly traded U.S. companies; widely used as a benchmark for the U.S. equity market.
DJIA — The Dow Jones Industrial Average, a price-weighted stock index of 30 large U.S. companies, often used as a headline indicator of the U.S. stock market.
Nasdaq Composite — A stock market index composed largely of companies listed on the Nasdaq exchange, with especially heavy representation from technology and growth stocks.
STOXX 600 — A broad European stock index that tracks 600 large, mid, and small companies across Europe.
Nikkei 225 — A major Japanese stock market index tracking 225 prominent Japanese companies.
TSX — Canada’s main stock market benchmark, often referring to the S&P/TSX Composite Index.
CAC 40 — France’s main stock market index, tracking 40 major French companies.
DAX — Germany’s main stock market index, tracking major German listed companies.
FTSE 100 — The leading U.K. stock market index, tracking 100 large companies listed in London.
Shanghai Composite — A major Chinese stock index tracking stocks listed on the Shanghai Stock Exchange.
Shenzhen Component — A major Chinese stock index tracking companies listed on the Shenzhen Stock Exchange.
ACWI ex-U.S. Index — The MSCI All Country World Index excluding the United States; a benchmark for developed and emerging equity markets outside the U.S.
10-Year Yield — The interest rate paid on a 10-year government bond; a key benchmark for long-term borrowing costs and valuation.
Bund Yield — The yield on German government bonds, often used as a benchmark for euro-area sovereign debt.
Gilt Yield — The yield on U.K. government bonds, commonly called gilts.
OAT Yield — The yield on French government bonds.
Policy Rate — The benchmark interest rate set by a central bank to influence borrowing costs, inflation, and economic activity.
Basis Point (bp) — One one-hundredth of a percentage point; 25 basis points equals 0.25%.
Relative Strength — A measure of how a market, sector, or asset performs compared with another market or benchmark.
Overweight / Underweight / Neutral — Portfolio positioning terms: overweight means above benchmark allocation, underweight means below benchmark allocation, and neutral means roughly in line with the benchmark.